ET Stock in November 2026: Distribution, Yield, and Outlook
Founder of Tritonix.ai. Former Hedge Fund Analyst with 10+ years of experience managing over $1B AUM across insurance portfolios and private funds. Specializes in institutional-grade fundamental analysis and long-term capital allocation.
What ET stock is pricing after the November 12 close
ET stock is the common units of Energy Transfer LP, the Dallas-based midstream partnership that owns one of the largest U.S. networks of natural gas, NGL, crude oil, and refined-product pipelines. The units now trade on the Texas Stock Exchange under the ticker ET, after Energy Transfer transferred its primary listing from the New York Stock Exchange on October 5, 2026. The ticker did not change.
The units closed at $19.42 on Thursday, November 12, 2026. Yahoo Finance and StockAnalysis both show the session down $0.03, or 0.15%, from the prior close of $19.45. Yahoo lists a day range of $19.35 to $19.64 and volume of 5.97 million units, below the 8.67 million three-month average. That Thursday cash close is the latest official U.S. session available as of Friday, November 13, 2026.
At that price, Yahoo Finance put the market capitalization at about $66.89 billion. Trailing twelve-month revenue was $124.53 billion, net income available to common unitholders was $5.23 billion, and diluted earnings per unit were $1.51. The trailing P/E ratio was 12.86, with a forward distribution and yield of $1.37 and 7.04%.
The 52-week range is $16.18 to $21.84, putting the close about 11% below the high and about 20% above the low. Yahoo Finance's trailing total return, including distributions, was 26.35% year to date and 25.66% over one year as of November 12, versus 10.91% and 10.82% for the S&P 500.
| Metric | Value as of Nov. 12, 2026 close |
|---|---|
| Close | $19.42 |
| Session change | -$0.03 (-0.15%) |
| Day range | $19.35–$19.64 |
| Volume / 3-month average | 5.97M / 8.67M |
| Market cap | $66.89B |
| Trailing P/E | 12.86 |
| Diluted EPS (TTM) | $1.51 |
| Forward distribution / yield | $1.37 / 7.04% |
| 50-day / 200-day moving averages | $20.48 / $19.74 |
| 52-week range | $16.18–$21.84 |
| Beta (5-year monthly) | 0.60 |
Source: Yahoo Finance quote and key statistics pages, session of November 12, 2026.
ET stock at $19.42 is offering a 7.04% forward yield with 2.1x third-quarter coverage, but the units are trading below both major moving averages after the early-November pullback.
The tape has cooled since late October. Yahoo Finance's historical prices show a $20.91 close on October 30, a slide after the November 3 earnings report, a $18.92 close on the November 6 ex-dividend date, and a rebound to $19.42. The units now sit below the $20.48 50-day and $19.74 200-day moving averages. Investors who want a rules-based read on that trend can check the setup in Tritonix’s AI technical analysis tools.
Wall Street is still more constructive than the chart. Yahoo Finance lists a one-year average target of $24.74, with a low of $22.00 and a high of $28.00. StockAnalysis reports the same average from 23 analysts, a "Strong Buy" consensus, and about 27% implied upside. On November 10, Yahoo recorded Scotiabank maintaining Sector Outperform while cutting its target from $24 to $23.
{
  "type": "line",
  "title": "ET Stock Closing Price Around the Q3 2026 Report",
  "index": "Date",
  "categories": ["Close"],
  "data": [
    {"Date": "2026-09-30", "Close": 19.77},
    {"Date": "2026-10-09", "Close": 20.41},
    {"Date": "2026-10-16", "Close": 20.26},
    {"Date": "2026-10-23", "Close": 20.45},
    {"Date": "2026-10-27", "Close": 20.41},
    {"Date": "2026-10-30", "Close": 20.91},
    {"Date": "2026-11-02", "Close": 20.34},
    {"Date": "2026-11-03", "Close": 20.16},
    {"Date": "2026-11-04", "Close": 19.46},
    {"Date": "2026-11-06", "Close": 18.92},
    {"Date": "2026-11-10", "Close": 19.43},
    {"Date": "2026-11-12", "Close": 19.42}
  ],
  "source": "Yahoo Finance historical prices, unadjusted session closes through November 12, 2026",
  "note": "November 3 is the Q3 earnings date; November 6 is the $0.3425 ex-distribution date."
}
The distribution is a partnership payout, and coverage is still wide
Energy Transfer is a publicly traded limited partnership, not a C-corporation. The cash it sends to common unitholders is a distribution, not a corporate dividend, and tax reporting generally comes on a Schedule K-1 rather than a Form 1099-DIV. The partnership still maintains a K-1 tax package page for unitholders. This is not tax advice; the K-1 is the document that matters at tax time.
In October 2026, Energy Transfer announced a quarterly cash distribution of $0.3425 per common unit, or $1.37 annualized, for the quarter ended September 30, 2026. The third-quarter 2026 earnings release called this the Partnership's twentieth consecutive increase and said the payout was up more than 3% from the third quarter of 2025. Yahoo Finance lists the ex-distribution date as November 6, 2026, and the payment date as November 19, 2026, producing the 7.04% forward yield at the November 12 close.
The more important number for an MLP is distributable cash flow, not the earnings payout ratio. For the third quarter, Energy Transfer reported DCF attributable to partners, as adjusted, of $2.52 billion, up 33% from $1.90 billion. Distributions to limited partners were $1.180 billion, or $1.181 billion including the general partner, implying coverage of about 2.1 times. For the first nine months of 2026, adjusted DCF attributable to partners was $7.813 billion against $3.515 billion of total partner distributions.
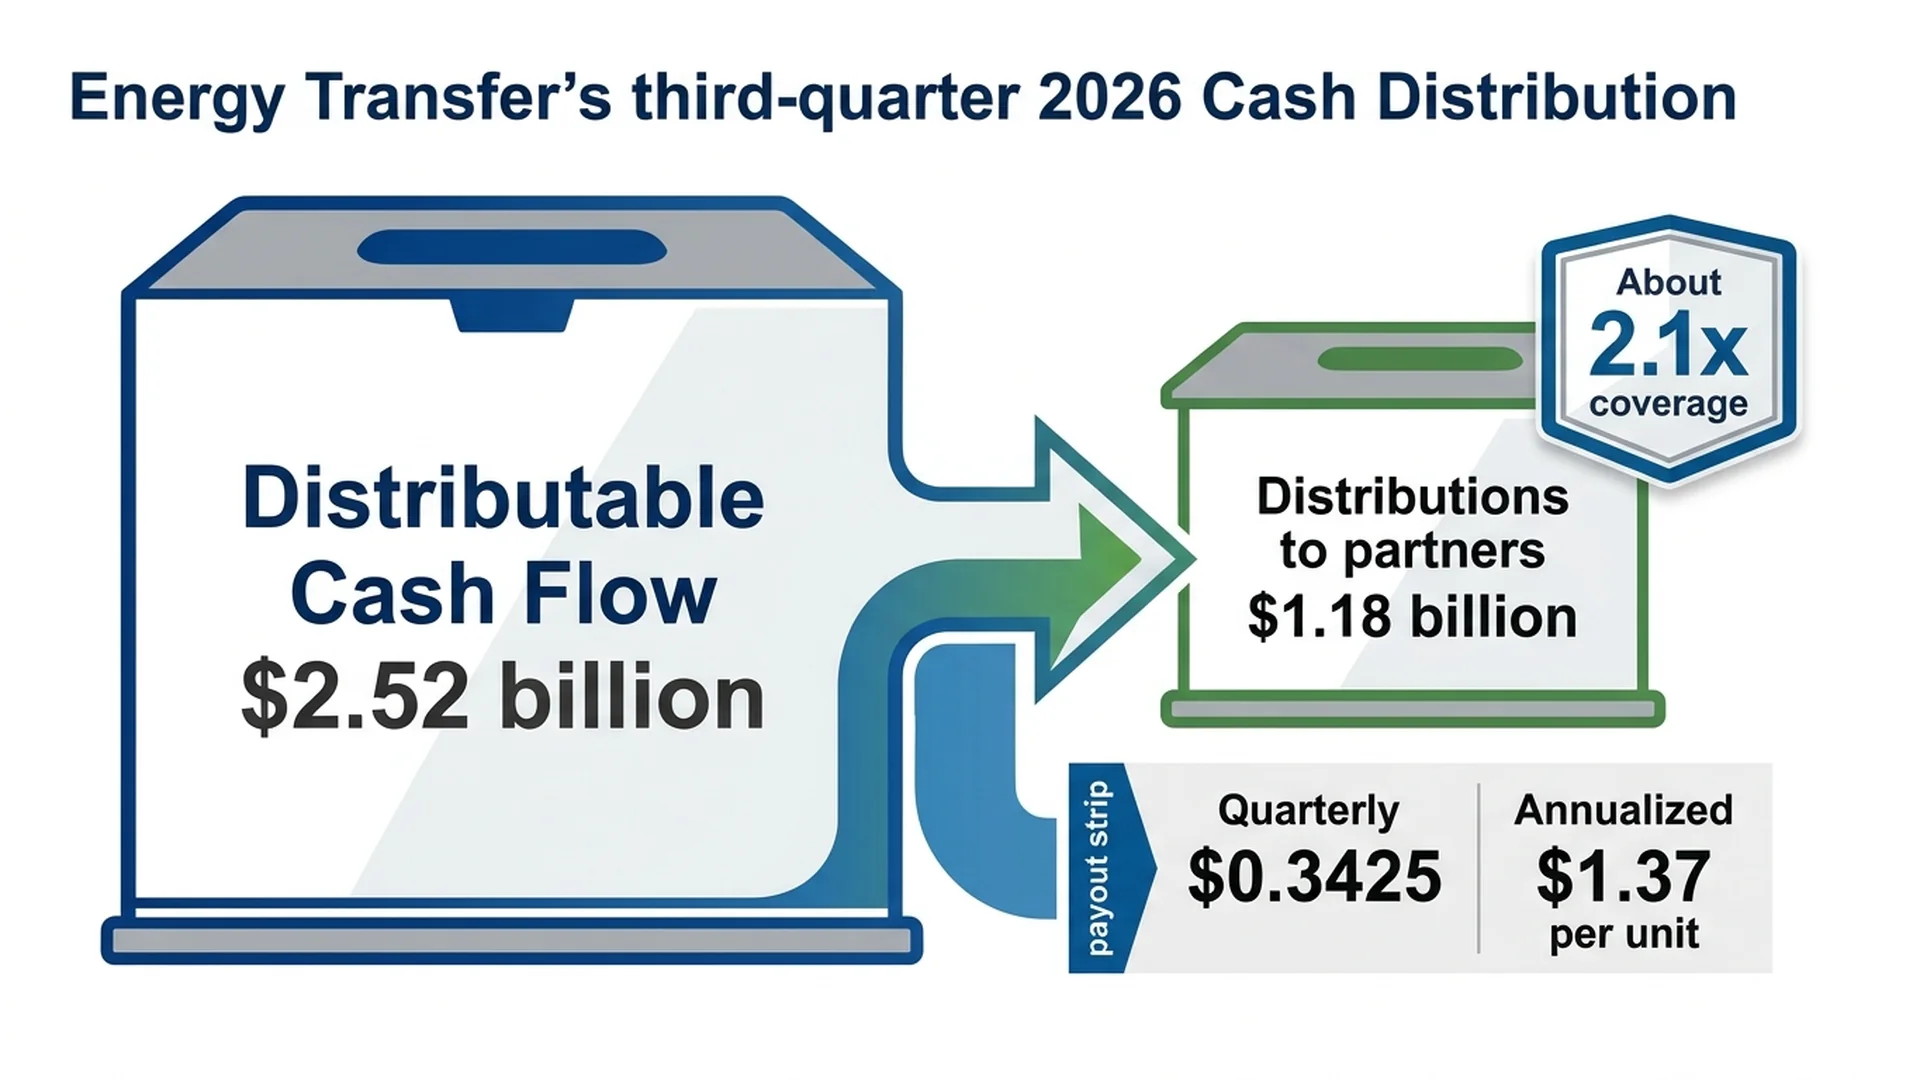
AI generated infographic of Energy Transfer's third-quarter 2026 payout math: $2.52 billion of adjusted DCF against $1.18 billion of partner distributions, or about 2.1 times coverage.
Incentive distribution rights are not the squeeze they once were on Energy Transfer's own common units. The same earnings release shows only $1 million going to the general partner in the third quarter, beside $1.180 billion for limited partners. Energy Transfer does still own the general partner interests and IDRs of Sunoco LP, plus about 28 million SUN common units, and the general partner plus about 46 million common units of USA Compression Partners.
The 7.04% yield is being funded by cash flow that covered the third-quarter payout by about 2.1 times, leaving room for both the raise and the growth budget.
That coverage is the main support under the income case, and the number to watch if 2027 growth spending climbs toward the $7 billion the Partnership has flagged.
Cash flow, segment mix, and the next wave of projects
The third-quarter report, released on November 3, 2026, was strong on midstream cash measures even if net income per common unit was a more modest $0.33. Net income attributable to partners was $1.21 billion, up from $1.02 billion. Adjusted EBITDA was $5.03 billion, up 31% from $3.84 billion, and growth capital expenditures were $1.30 billion.
Management also raised the 2026 outlook. The Partnership now expects full-year adjusted EBITDA of $19.7 billion to $19.9 billion, versus a previous range of $18.8 billion to $19.1 billion, an increase of $0.85 billion at the midpoint. It expects $5.4 billion to $5.6 billion of growth capital in 2026 and about $7 billion in 2027.
Volume trends did some of the work. Versus the third quarter of 2025, intrastate transportation volumes were up 14% and midstream gathered volumes were up 6%, both partnership records. NGL transportation volumes rose 6%, NGL exports rose 9%, and NGL fractionation volumes rose 5%.
| Segment adjusted EBITDA ($ millions) | Q3 2026 | Q3 2025 |
|---|---|---|
| Intrastate transportation and storage | 346 | 230 |
| Interstate transportation and storage | 500 | 431 |
| Midstream | 864 | 751 |
| NGL and refined products transportation and services | 1,224 | 1,054 |
| Crude oil transportation and services | 871 | 746 |
| Investment in Sunoco LP | 1,049 | 489 |
| Investment in USAC | 198 | 160 |
| All other | (21) | (23) |
| Adjusted EBITDA (consolidated) | 5,031 | 3,838 |
Source: Energy Transfer third-quarter 2026 earnings release, November 3, 2026. Figures are segment adjusted EBITDA as reported.
The mix is diversified, not a pure fee-only pipeline story. NGL and refined products led at $1.224 billion, with midstream at $864 million and crude oil at $871 million. The investment in Sunoco LP more than doubled, to $1.049 billion from $489 million, so consolidated EBITDA includes cash that is not fully attributable to ET partners.
{
  "type": "bar",
  "title": "Energy Transfer Q3 2026 Segment Adjusted EBITDA",
  "index": "Segment",
  "categories": ["Q3 2026", "Q3 2025"],
  "data": [
    {"Segment": "Intrastate", "Q3 2026": 346, "Q3 2025": 230},
    {"Segment": "Interstate", "Q3 2026": 500, "Q3 2025": 431},
    {"Segment": "Midstream", "Q3 2026": 864, "Q3 2025": 751},
    {"Segment": "NGL and refined", "Q3 2026": 1224, "Q3 2025": 1054},
    {"Segment": "Crude oil", "Q3 2026": 871, "Q3 2025": 746},
    {"Segment": "Sunoco LP", "Q3 2026": 1049, "Q3 2025": 489},
    {"Segment": "USAC", "Q3 2026": 198, "Q3 2025": 160}
  ],
  "source": "Energy Transfer third-quarter 2026 earnings release, November 3, 2026",
  "note": "Segment adjusted EBITDA, $ millions. All other, a $21 million Q3 2026 loss, is omitted. Consolidated adjusted EBITDA was $5.031 billion."
}
The project list ties the raised guide to the heavier 2027 budget. In October, Energy Transfer announced a bolt-on acquisition of Vaquero Midstream LLC for about $2.6 billion in cash and equity, expected to close in the fourth quarter of 2026, subject to regulatory approval and customary conditions.
Organic projects are moving as well. Phase I of the Hugh Brinson Pipeline entered full service on September 1, 2026, ahead of schedule, with Phase II still expected in the first quarter of 2027. The 275 MMcf/d Mustang Draw II plant in the Midland Basin entered service in October. In November, the Partnership announced the 200 MMcf/d Bear II plant in the Delaware Basin, due in the third quarter of 2027, and reached FID on the 215-mile South Mississippi Pipeline, a 36-inch line with 1.2 Bcf/d of capacity and an expected cost of about $1.6 billion, backed by long-term, demand-based contracts.
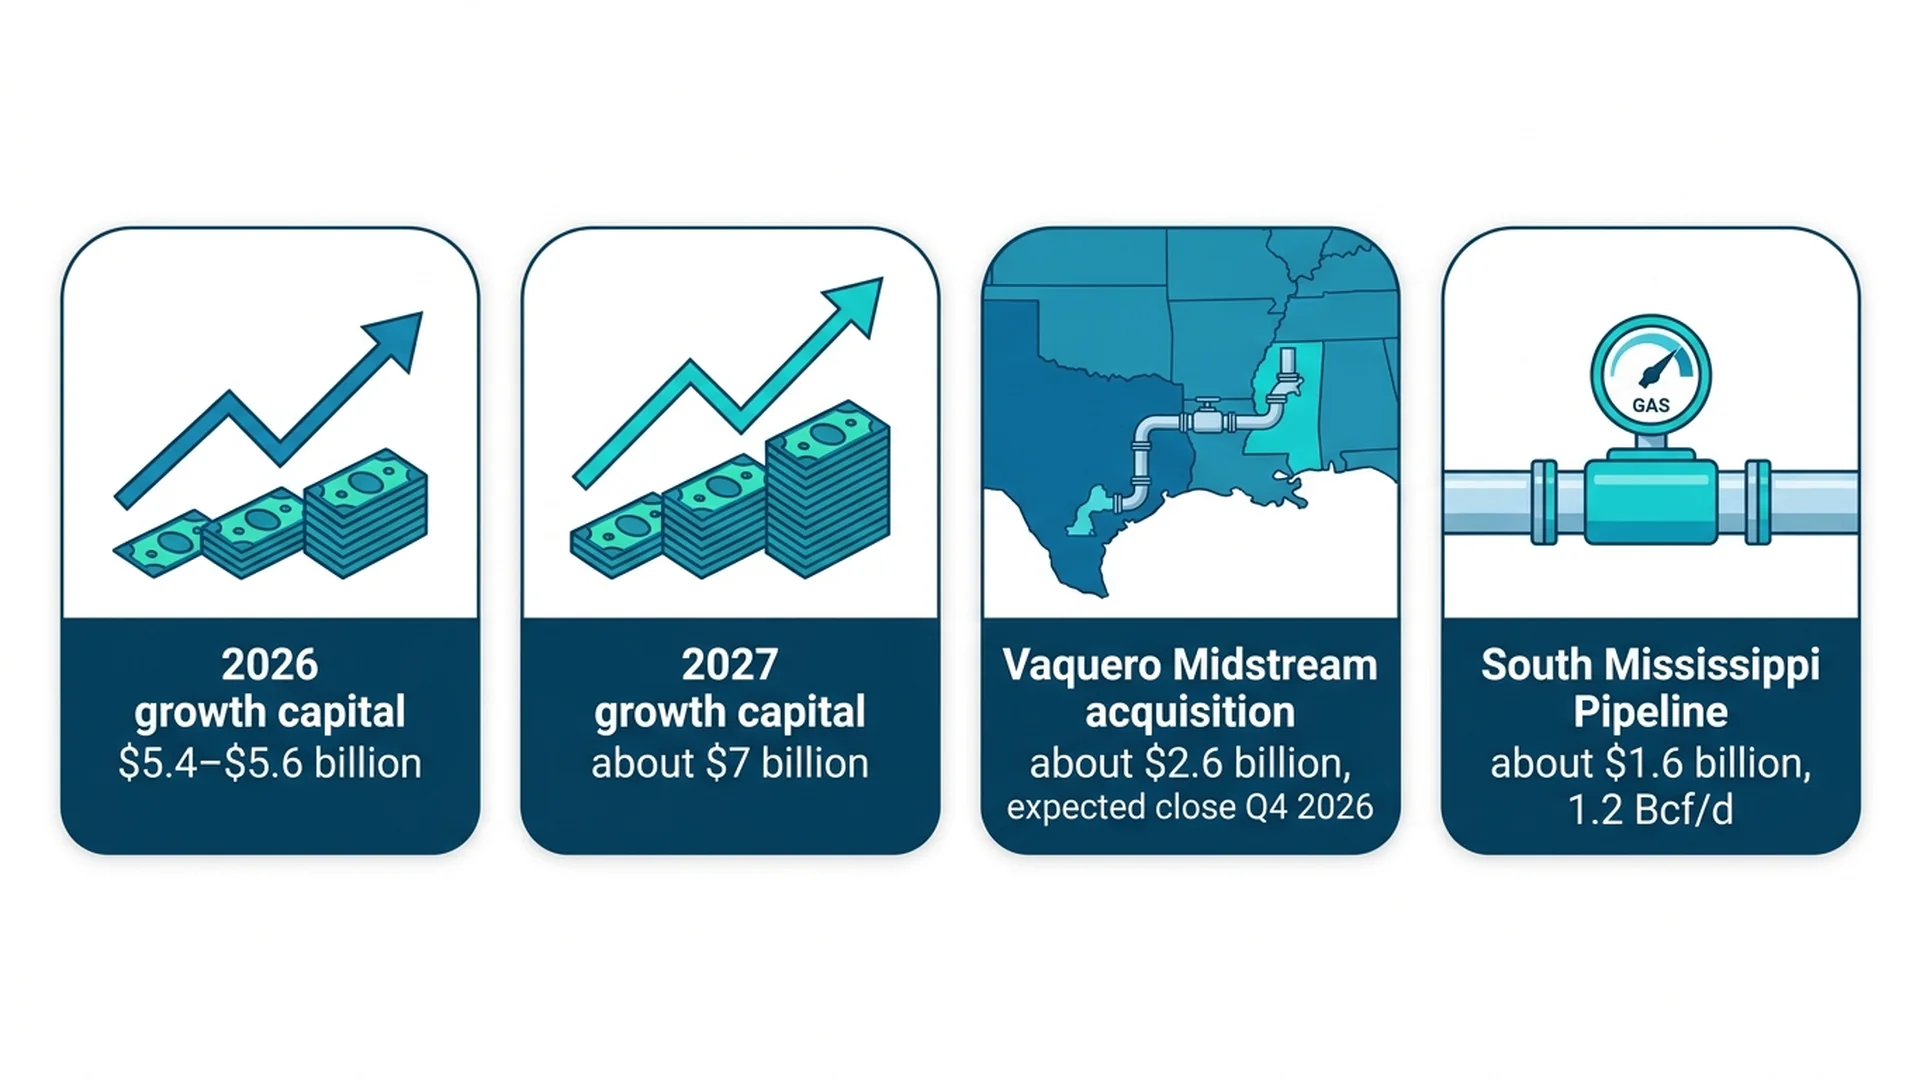
AI generated infographic of Energy Transfer's published growth budget and two large commitments: 2026 growth capital of $5.4–$5.6 billion, about $7 billion of 2027 growth capital, the $2.6 billion Vaquero Midstream acquisition, and the $1.6 billion South Mississippi Pipeline.
The raised 2026 EBITDA guide and the 2.1x coverage are already visible; the 2027 capital step-up is the part of the story that still has to earn its keep.
How ET stock stacks up against midstream peers
The valuation question is whether ET stock is cheap relative to other large midstream partnerships after the pullback, or cheap for a reason. On the November 12 close, its 7.04% forward yield sat between Enterprise Products Partners and MPLX.
| Partnership | Close (Nov. 12) | Market cap | Forward yield | Trailing P/E | EV/EBITDA | Average target |
|---|---|---|---|---|---|---|
| Energy Transfer (ET) | $19.42 | $66.89B | 7.04% | 12.86 | 8.50 | $24.74 |
| Enterprise Products (EPD) | $37.40 | $80.66B | 5.99% | 12.37 | 10.79 | $41.67 |
| MPLX (MPLX) | $56.59 | $57.33B | 8.56% | 13.22 | 13.39 | $62.31 |
Source: Yahoo Finance and Yahoo key statistics for ET, November 12, 2026 close. StockAnalysis EPD and MPLX statistics, citing S&P Global Market Intelligence and last updated November 12, 2026.
On a simple screen, ET looks cheaper on trailing enterprise value to EBITDA, at 8.50 times versus 10.79 times for EPD and 13.39 times for MPLX. The comparison is imperfect. Yahoo's ET enterprise value of $154.73 billion consolidates Sunoco LP and USA Compression, so the multiple is not a clean look-through to cash available to ET unitholders. Trailing P/E ratios are closer: 12.86 for ET, 12.37 for EPD, and 13.22 for MPLX.
Yield tells a different story. EPD's 5.99% yield is lower. MPLX's 8.56% yield is higher, so Energy Transfer is the middle-yield name in this trio, with the largest Street-implied upside. Yahoo's $24.74 average target is about 27% above the last close, versus about 11% implied upside in the StockAnalysis targets for EPD ($41.67) and MPLX ($62.31).
ET stock screens cheaper than EPD and MPLX on trailing EV/EBITDA, but the discount has to be judged after consolidating Sunoco and USAC and after funding a heavier 2027 growth budget.
A discounted multiple and a mid-7% yield can coexist with a soft chart because the market is paying for the distribution and backlog, and withholding a peer multiple until the buildout proves it will not compress coverage.
Leverage, funding, and the risks that actually matter
Energy Transfer remains a heavily financed midstream franchise. The Form 10-Q for the quarter ended September 30, 2026 reported total debt of $68.850 billion and a credit-facility leverage ratio of 2.83 times, with the Partnership in compliance with its debt covenants at quarter-end. Yahoo Finance's broader debt figure of $70.71 billion is higher than the 10-Q total, a reminder to use the Partnership's own covenant math when judging headroom.
The company is still active in the bond market. On November 5, 2026, Energy Transfer announced the pricing of $2.7 billion of senior notes: $900 million of 5.450% notes due 2032, $900 million of 5.900% notes due 2037, and $900 million of 6.550% notes due 2057. Settlement is expected on November 20, 2026, with about $2.68 billion of net proceeds, before expenses, earmarked to refinance commercial paper and credit-facility borrowings and for general partnership purposes.
The first risk is not an imminent covenant breach. It is a large debt load, rising growth capital, and refinancing costs that stay elevated if coupons in the mid-5% to mid-6% range become the clearing level. Interest already matters: the third-quarter reconciliation included interest expense, net of amounts capitalized, of $944 million.
The second risk is volume and commodity exposure. A large share of midstream cash flow is fee-based, but the midstream and NGL segments still move with gathered volumes, NGL prices, and export demand. Energy Transfer's release attributed part of the midstream gain to higher volumes and higher NGL and natural gas prices. If those fade, coverage can compress even if the pipeline map does not shrink.
The third risk is project execution. Vaquero still has to close, and Hugh Brinson Phase II, Bear II, and the South Mississippi Pipeline still have to be built on budget and on schedule. A $7 billion 2027 growth-capital plan raises the cost of permitting delays, construction inflation, or slower producer ramps than the FID models assume.
The fourth risk is the partnership wrapper. K-1s and state filings can limit the buyer base, especially in tax-exempt or retirement accounts. Yahoo Finance's holders page, citing Refinitiv, shows institutions holding 32.48% of the units and insiders holding 10.29%, with 1,425 institutions reported. Short interest as of September 30, 2026 was 26.94 million units, or 0.87% of the float. The largest reported holders included Morgan Stanley, with 85.61 million units as of June 30, 2026, ALPS Advisors, with 84.78 million as of September 30, 2026, and JPMorgan Chase, with 81.08 million as of June 30, 2026. Readers who want to track those 13F changes can use Tritonix’s institutional smart money dashboard.
The balance-sheet risk is not a 2.83x covenant ratio on its own; it is whether coverage stays comfortably above 1.5 times while 2027 capex and refinancing needs rise together.
What unitholders should watch into year-end
The next fundamental checkpoint is whether fourth-quarter distributable cash flow keeps coverage near the 2.1 times third-quarter level as Vaquero and the 2026 growth-capital range of $5.4 billion to $5.6 billion play out. A still-wide ratio would support the distribution increases as a trend. A tightening toward 1.5 times would change the income math even if the headline yield stayed near 7%.
Project delivery is the second test. Hugh Brinson Phase II is slated for the first quarter of 2027, Bear II for the third quarter of 2027, and the South Mississippi Pipeline remains a $1.6 billion construction story. On-time, under-budget execution would help confirm the raised EBITDA guide; slippage would justify keeping the multiple discounted to EPD.
The chart is the third test. ET stock is below its $20.48 50-day average and just under its $19.74 200-day average after falling from the October 30 close of $20.91. Reclaiming those averages would not, by itself, validate the $24.74 target. A break below the November 6 close of $18.92, toward the $16.18 52-week low, would signal that the reset is still underway.
None of this is a buy or sell recommendation. ET stock is a high-yielding midstream partnership with covered distributions, a raised 2026 EBITDA outlook, and a heavier forward capital plan. The November 12 close of $19.42 prices that mix with less enthusiasm than the average Street target, and with more caution than the 2.1 times coverage figure alone would suggest.
FAQ
What is ET stock?
ET stock is the common units of Energy Transfer LP, a Dallas-based midstream partnership. The units trade on the Texas Stock Exchange under the ticker ET after a listing transfer from the NYSE on October 5, 2026. They closed at $19.42 on Thursday, November 12, 2026, according to Yahoo Finance and StockAnalysis.
Does Energy Transfer pay a dividend?
Energy Transfer pays a quarterly cash distribution, not a corporate dividend, and unitholders generally receive a Schedule K-1. In October 2026 it declared $0.3425 per common unit, or $1.37 annualized, its twentieth consecutive increase. Yahoo Finance listed a 7.04% forward yield at the November 12 close, an ex-distribution date of November 6, 2026, and a payment date of November 19, 2026.
Is Energy Transfer's distribution covered by cash flow?
Yes, on the Partnership's preferred midstream measure. The November 3, 2026 earnings release showed third-quarter distributable cash flow attributable to partners, as adjusted, of $2.52 billion, versus $1.180 billion of distributions to limited partners, or about 2.1 times coverage. Nine-month adjusted DCF was $7.813 billion against $3.515 billion of total distributions to partners.
Why did ET stock pull back in early November 2026?
Energy Transfer reported third-quarter results on November 3, 2026, including adjusted EBITDA of $5.03 billion, up 31%, and net income of $0.33 per common unit. Yahoo Finance historical prices show the units closing at $20.91 on October 30, then slipping to $18.92 on the November 6 ex-distribution date and $19.42 on November 12, below the $20.48 50-day and $19.74 200-day moving averages.
How does ET stock compare with midstream peers?
At the November 12, 2026 close, ET's 7.04% forward yield sat between Enterprise Products Partners' 5.99% and MPLX's 8.56%. Yahoo Finance listed ET at 8.50 times trailing EV/EBITDA, below EPD's 10.79 and MPLX's 13.39 on StockAnalysis, though ET's $154.73 billion enterprise value consolidates Sunoco LP and USA Compression. The average Street target for ET was $24.74.