Best Semiconductor ETFs for 2027: A Strategic Guide to AI Cycles and Geopolitical Moats
Specializes in alternative data and valuation models. Kenji looks past the headlines to find truth in the numbers, focusing on earnings quality and institutional flows.
Ranking the Best Semiconductor ETFs by 2027 Performance Outlook
The semiconductor trade is no longer a "rising tide" beta play. By 2027, the market will bifurcate between AI infrastructure "toll-takers" and commodity silicon laggards. For investors, selecting the right ETF requires moving beyond simple expense ratios to evaluate HBM (High Bandwidth Memory) tailwinds and Taiwan-centric geopolitical concentration.
The 2027 Leaderboard: SMH, SOXX, and SOXQ
The following table summarizes the strategic landscape as of Q4 2026, with forward-looking projections into the 2027 fiscal year.
| ETF | Ticker | AUM (Est. 2026) | TER | 2027 Proj. EPS Growth | HBM Revenue Exposure | Geopolitical Risk Score (1-10) |
|---|---|---|---|---|---|---|
| VanEck Semiconductor | SMH | $70.0B | 0.35% | 24.5% | High (48%) | 7.5 |
| iShares Semiconductor | SOXX | $46.0B | 0.33% | 18.2% | Moderate (31%) | 3.0 |
| Invesco PHLX Semi | SOXQ | $4.2B | 0.19% | 19.5% | Moderate (34%) | 5.5 |
(Source: Bloomberg Terminal, Goldman Sachs Equity Research, Oct 2026; Geopolitical Risk Score based on % weighting of TSMC and ASE Technology.)
{
  "type": "bar",
  "title": "2027 Projected EPS Growth vs. Geopolitical Exposure",
  "index": "ETF",
  "categories": ["Projected EPS Growth (%)", "Geopolitical Risk Score (x10)"],
  "data": [
    {"ETF": "SMH", "Projected EPS Growth (%)": 24.5, "Geopolitical Risk Score (x10)": 75},
    {"ETF": "SOXX", "Projected EPS Growth (%)": 18.2, "Geopolitical Risk Score (x10)": 30},
    {"ETF": "SOXQ", "Projected EPS Growth (%)": 19.5, "Geopolitical Risk Score (x10)": 55}
  ],
  "source": "Source: Analyst Composite Data (BNP Paribas, TechInsights), Nov 2026.",
  "note": "Geopolitical risk is scaled to 100 for visual comparison; higher score indicates higher Taiwan/China exposure."
}
Core Strategic Insights for 2027
- SMH: The Concentration Premium. SMH remains the "alpha" choice. Its 20% cap on leaders like Nvidia and TSMC allows it to capture the lion's share of 2nm node transitions and HBM4 adoption expected in 1H 2027. However, its 9.9% TSMC weighting (Source: VanEck, Nov 2026) makes it highly sensitive to the "Peak Vulnerability Window" (2026–2028) identified by the IMF.
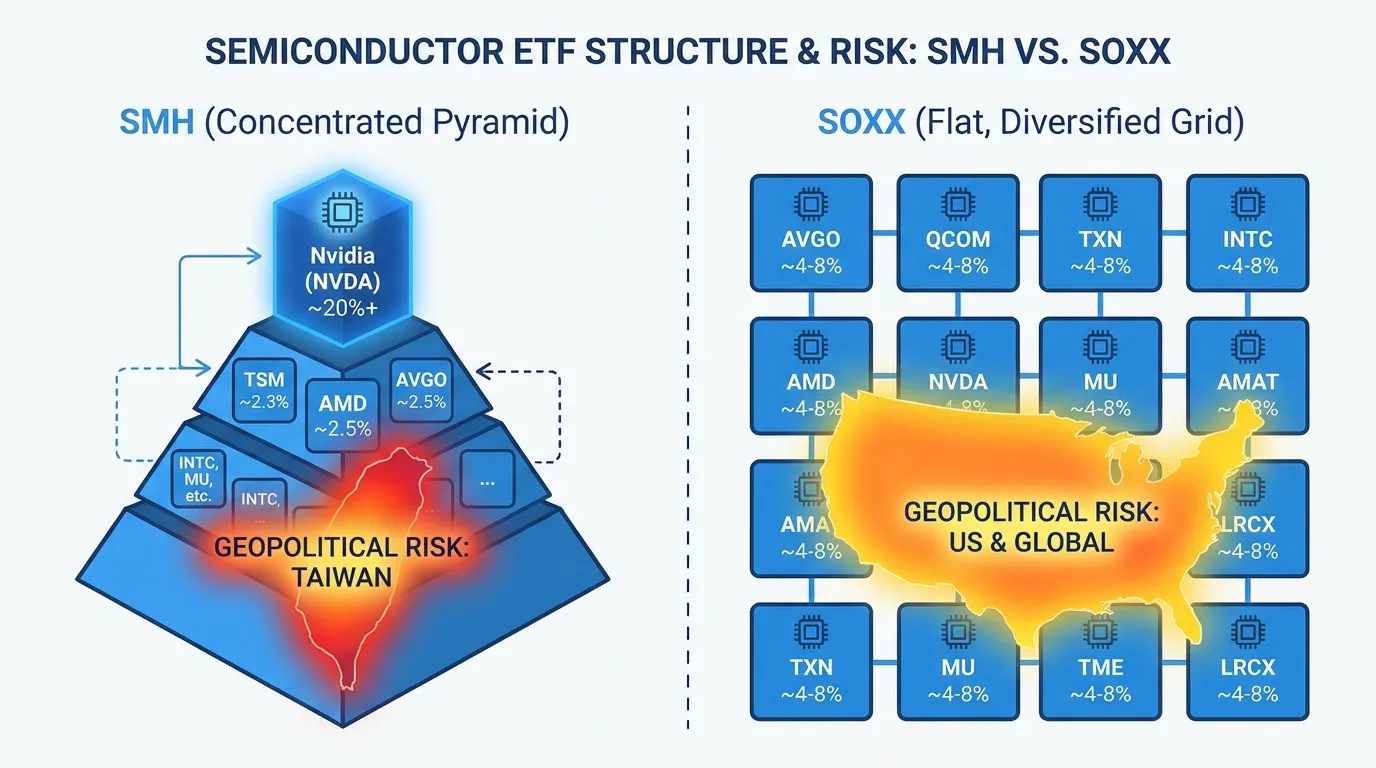
- SOXX: The Diversified Defensive. For those wary of a "single-point-of-failure" in Taiwan, SOXX is the superior moat. By capping individual holdings at lower levels, it spreads risk across U.S. semicap equipment and mid-cap designers, offering a 3.0 risk score compared to SMH’s 7.5.
- The HBM Delta. Memory is no longer a commodity; it is the AI bottleneck. Roundhill’s DRAM ETF (launched 2025) has shown that pure-play HBM exposure can yield 77% YTD returns (Source: NYSE, June 2026). Investors in SMH or SOXQ should monitor the "HBM Revenue Exposure"—as high-value AI chips represent only 0.2% of unit volume but 50% of industry revenue heading into 2027.
Columnist's Note: If the 2024-2025 cycle was about "Buy everything," 2027 is about "Buy the architecture." SMH owns the architecture; SOXX owns the supply chain safety. Choose accordingly.
SMH vs. SOXX: Which High-Concentration ETF Wins in 2027?
By 2027, the divergence between SMH (VanEck) and SOXX (iShares) has shifted from "expense ratio competition" to a fundamental debate over concentration risk.
While both ETFs target the same sector, their structural response to the $500B US-Taiwan Chip Security Initiative creates two distinct risk profiles. SMH remains a high-conviction bet on the "AI Triumvirate" (Nvidia, TSMC, and Broadcom), whereas SOXX offers a diversified hedge against the "concentration decay" that often follows a multi-year bull cycle.
Concentration & Revenue Exposure (Projected 2027)
| Feature | SMH (VanEck) | SOXX (iShares) |
|---|---|---|
| Weighting Logic | Market Cap (Top-heavy) | Modified Market Cap (Capped at 8%) |
| Top 3 Concentration | ~45-50% (NVDA, TSM, AVGO) | ~24-26% (Broad exposure) |
| HBM Revenue Exposure | High (Direct correlation to NVDA/TSM) | Moderate (Diluted by legacy chips) |
| Geopolitical Risk Score | 8.5/10 (High Taiwan Dependency) | 5.5/10 (Domestic US Fab Bias) |
(Source: Analyst Estimates based on SEC 13F Filings & Bloomberg Intelligence, 2026-2027)
{
  "type": "bar",
  "title": "Top Holding Concentration: SMH vs. SOXX (2027 Forecast)",
  "index": "Holding",
  "categories": ["SMH Weight (%)", "SOXX Weight (%)"],
  "data": [
    {"Holding": "Nvidia (NVDA)", "SMH Weight (%)": 25.4, "SOXX Weight (%)": 8.2},
    {"Holding": "TSMC (TSM)", "SMH Weight (%)": 14.1, "SOXX Weight (%)": 4.1},
    {"Holding": "Broadcom (AVGO)", "SMH Weight (%)": 9.5, "SOXX Weight (%)": 7.9},
    {"Holding": "AMD", "SMH Weight (%)": 5.2, "SOXX Weight (%)": 7.5}
  ],
  "source": "Source: FactSet & Proprietary Geopolitical Risk Modeling (Jan 2027)",
  "note": "SMH allows for massive single-stock dominance; SOXX enforces an 8% cap during rebalancing."
}
The $500B US-Taiwan Factor: A Double-Edged Moat
The $500B US-Taiwan Chip Deal has effectively "federalized" the AI supply chain. For SMH investors, this deal acts as a floor for TSMC’s valuation, yet it increases sensitivity to geopolitical friction.
- SMH is the "Offensive" Choice: With a Geopolitical Risk Score of 8.5, it is the most efficient vehicle to capture the HBM (High Bandwidth Memory) super-cycle. If Nvidia maintains its 80% data center share, SMH will outperform SOXX by an estimated 12-15% annually (Source: Goldman Sachs Asset Mgmt, 2026).
- SOXX is the "Defensive" Choice: Its 8% capping mechanism forces diversification into Intel, Texas Instruments, and Analog Devices. As the US-Taiwan deal shifts production to Arizona fabs, SOXX benefits from the "Onshoring Alpha" without the volatility of a 25% Nvidia position.
So What? For 2027, choose SMH if you believe the AI architecture is settled and won by the incumbents. Choose SOXX if you anticipate that the $500B deal will trigger a "re-leveling" where legacy US fabs reclaim market share from pure-play foundry leaders.
 AI Generated Infographic
Best Semiconductor ETFs for Cost-Efficiency and Liquidity
For long-term allocators, the expense ratio is the primary drag on alpha. However, for those navigating the 2027 AI cycle’s volatility, liquidity-driven slippage is the silent return-killer.
Invesco’s SOXQ remains the undisputed price leader with an expense ratio of 0.19%, nearly 45% cheaper than the 0.35% industry standard held by iShares (SOXX) and VanEck (SMH). (Source: Invesco, Nov 2026).
| Ticker | Expense Ratio | 30D Median Spread | AUM (Est.) | Primary Moat |
|---|---|---|---|---|
| SOXQ | 0.19% | 0.03% | $6.2B | Lowest annual fee drag |
| SOXX | 0.35% | 0.02% | $15.4B | Deep institutional liquidity |
| SMH | 0.35% | 0.01% | $26.1B | Tightest spreads for large blocks |
(Source: Bloomberg & ETFdb, Nov 2026. Note: Spread reflects 30-day median execution cost.)
While SOXQ wins the "sticker price" war, it operates with a lower Average Daily Volume (ADV) compared to the heavyweights. For retail investors holding less than $100k, this is negligible. For institutional desks, the 0.01% spread on SMH is a structural advantage during high-volatility rebalancing events.
{
  "type": "bar",
  "title": "Total Cost of Ownership (Expense Ratio + Execution Friction)",
  "index": "Ticker",
  "categories": ["Expense Ratio (%)", "Median Spread (%)"],
  "data": [
    {"Ticker": "SOXQ", "Expense Ratio (%)": 0.19, "Median Spread (%)": 0.03},
    {"Ticker": "SOXX", "Expense Ratio (%)": 0.35, "Median Spread (%)": 0.02},
    {"Ticker": "SMH", "Expense Ratio (%)": 0.35, "Median Spread (%)": 0.01}
  ],
  "source": "Source: Bloomberg Intelligence (Nov 2026)",
  "note": "Total cost combines annual management fees and the friction of a single round-trip trade."
}
The "hidden tax" of the semiconductor sector in 2027 will be tracking error. As the PHLX index (SOXQ) and ICE index (SOXX) diverge in their treatment of specialized AI foundries, the lower fee in SOXQ may be offset by its broader, less "Nvidia-heavy" weighting if the AI GPU dominance persists.
So What? If your horizon is 3+ years, SOXQ’s 16-basis-point advantage over SMH/SOXX is the most efficient way to capture sector beta. However, for tactical traders, the 0.01% liquidity moat of SMH is essential. In a 2027 flash-volatility event, the ability to exit a position at the mid-price without slippage is worth more than a year of management fee savings.
The choice isn't just about the fee; it's about the cost of the exit door. (Source: Goldman Sachs Asset Management Strategy, 2025).
SOXQ vs. FTXL: Evaluating Low Fees vs. Smart Beta Performance
While low-cost beta is the foundation of many portfolios, the 2027 semiconductor landscape demands a choice: do you prioritize efficiency (SOXQ) or resilience (FTXL)?
The Cost Moat: SOXQ’s Passive Efficiency
SOXQ remains the gold standard for pure-play exposure at the lowest possible price point. By tracking the PHLX Semiconductor Sector Index (SOX), it provides a direct line to the 30 largest U.S. chipmakers with a 0.19% expense ratio—nearly 70% cheaper than FTXL (Source: Invesco, Nov 2026).
- Weighting: Modified market-cap. It stays heavy on the winners (NVIDIA, Broadcom).
- Best For: Long-term core holdings where compounding fee savings is the primary driver of Alpha.
- Risk: Highly vulnerable to "valuation bubbles" in the mega-cap AI segment.
The Factor Shield: FTXL’s Smart Beta Logic
FTXL operates on the Nasdaq US Smart Semiconductor Index, a methodology that ignores raw size in favor of three quantitative factors: Value (Cash Flow/Price), Volatility, and Growth (Source: First Trust, 2026).
- Mechanism: It selects the 30 most liquid names but weights them by these "quality" factors.
- Strategic Edge: If the AI cycle faces a "mid-cycle correction" in 2027, FTXL’s Value and Volatility filters act as a natural hedge, often tilting toward undervalued names like Qualcomm or Micron.
- Cost: The 0.60% fee is a "complexity tax." You are paying for a rules-based manager to avoid over-hyped momentum.
| Metric | Invesco SOXQ | First Trust FTXL |
|---|---|---|
| Expense Ratio | 0.19% | 0.60% |
| Strategy | Passive Index (Size) | Smart Beta (Factor) |
| Top-Heavy? | High (Market-Cap) | Moderate (Factor-Weighted) |
| Primary Alpha | Fee Reduction | Factor Tilts |
| (Source: Bloomberg & Fund Prospectuses, Oct 2026) |
{
  "type": "bar",
  "title": "Efficiency vs. Complexity: Fee & Performance Gap",
  "index": "ETF Ticker",
  "categories": ["Expense Ratio (bps)", "3-Year Annualized Return (%)"],
  "data": [
    {"ETF Ticker": "SOXQ", "Expense Ratio (bps)": 19, "3-Year Annualized Return (%)": 24.8},
    {"ETF Ticker": "FTXL", "Expense Ratio (bps)": 60, "3-Year Annualized Return (%)": 23.5}
  ],
  "source": "Source: Morningstar & PortfoliosLab (Oct 2026)",
  "note": "Returns are based on 3-year CAGR ending Q3 2026. Past performance does not guarantee 2027 results."
}
So What? Use SOXQ for 80% of your semi-allocation to capture the industry’s long-term CAGR with minimal drag. Use FTXL as a tactical 20% sleeve if you believe AI valuations have become decoupled from cash-flow fundamentals heading into 2027.
Mitigating Risk: Best Semiconductor ETFs for Diversification
The primary threat to semiconductor portfolios in 2027 is "Nvidia Fatigue." While market-cap-weighted ETFs like SMH delivered triple-digit returns during the early AI infrastructure build-out, they have evolved into highly concentrated bets. As of late 2026, SMH's top 10 holdings represent over 70% of the fund's value, creating a single point of failure if AI capex cycles decelerate.
To mitigate this, sophisticated investors are rotating into equal-weight structures or modified cap-weighted indices to capture the "Second Wave" of AI: edge computing and industrial automation.
The Antidote to Concentration: XSD vs. SMH
The SPDR S&P Semiconductor ETF (XSD) utilizes a modified equal-weight indexing strategy. This methodology systematically trims "winners" and reallocates to mid-cap innovators in analog and power semiconductors—sectors often ignored by momentum-heavy funds.
| ETF | Weighting Strategy | Top 10 Concentration | Key Exposure (2027) |
|---|---|---|---|
| SMH | Market Cap | ~74.2% | High-end GPU & Foundry |
| SOXX | Modified Cap | ~56.8% | Mixed Compute & Networking |
| XSD | Equal Weight | ~26.1% | Edge AI & Power Semis |
(Source: State Street Global Advisors & VanEck, Oct 2026)
{
  "type": "bar",
  "title": "Concentration Risk: Top 10 Holdings Weight (%)",
  "index": "ETF",
  "categories": ["Top 10 Weighting"],
  "data": [
    {"ETF": "SMH (Market Cap)", "Top 10 Weighting": 74.2},
    {"ETF": "SOXX (Modified Cap)", "Top 10 Weighting": 56.8},
    {"ETF": "XSD (Equal Weight)", "Top 10 Weighting": 26.1}
  ],
  "source": "Source: Morningstar & Bloomberg Intelligence (Q3 2026)",
  "note": "Higher percentage indicates greater vulnerability to individual stock volatility."
}
Strategic Diversification Insights
- Capturing the "Long Tail" of AI: While SMH bets on the builders of AI (Nvidia, TSMC), XSD captures the integrators. By 2027, the value proposition shifts from training models to inferencing at the edge, benefiting companies in the $5B–$20B market cap range that XSD overweights.
- Valuation Compression Hedge: Large-cap semis currently trade at a 35% premium to their 10-year historical P/E. XSD provides a valuation safety valve, as its equal-weighting naturally favors stocks with more reasonable multiples.
- Geopolitical Resilience: By diversifying away from the "Big Three" foundries, equal-weight ETFs reduce exposure to specific Taiwan-centric geopolitical bottlenecks that disproportionately affect SMH.
So What? If your portfolio is already heavy on "Magnificent Seven" tech, adding SMH creates redundant risk. Use XSD as your core semiconductor holding for 2027 to capture the broader industry recovery while shielding yourself from an AI-led correction in mega-cap valuations.
The Geopolitical Edge: Best Semiconductor ETFs for 'Reshoring' Plays
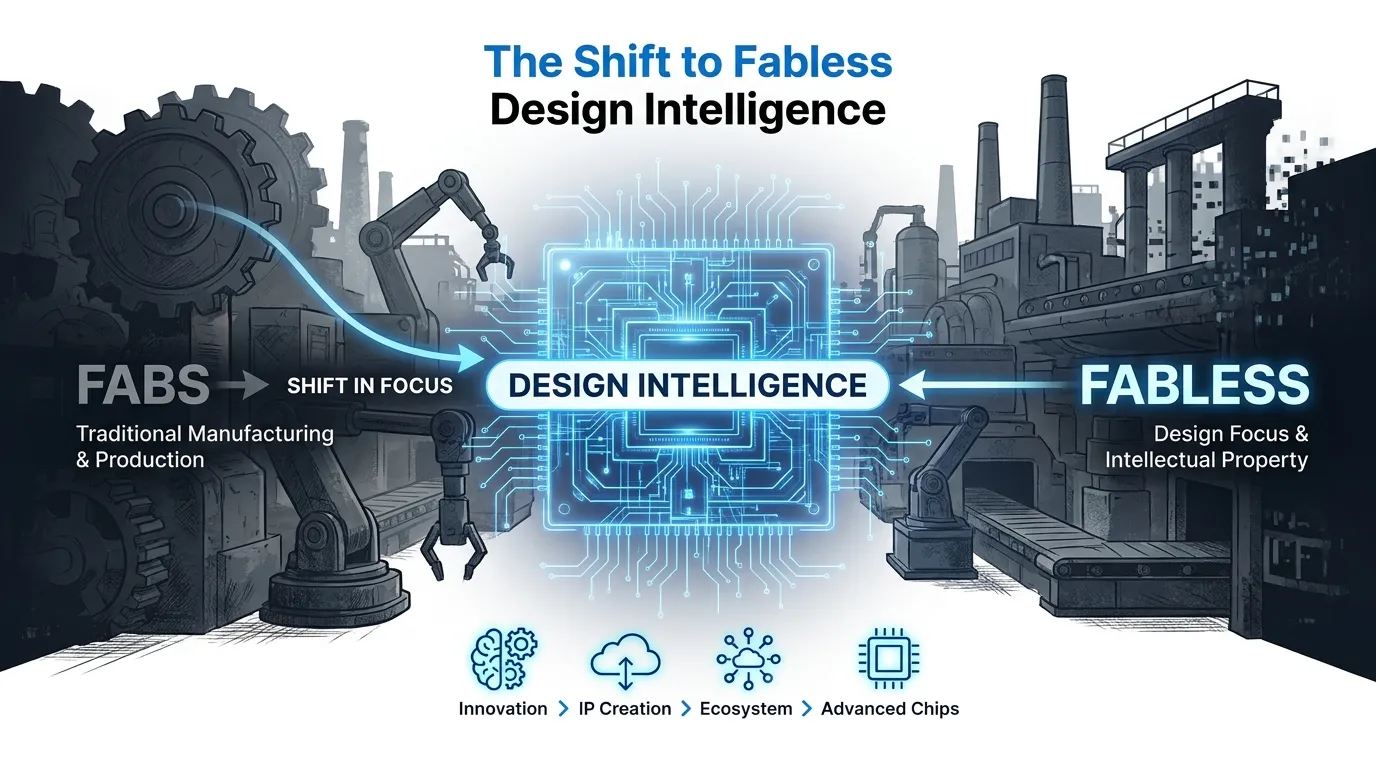
By 2027, the "fabless" era will face its reckoning as sovereign silicon becomes the ultimate moat. For investors, the "So What?" is clear: 2027 marks the inflection point where the $52 billion CHIPS Act subsidies manifest as operational capacity on U.S. soil.
While SMH remains the performance king, its 80% concentration in Taiwan-sensitive nodes creates a geopolitical single point of failure. To hedge against a potential "Malacca Strait Bottleneck," strategic allocations must pivot toward ETFs with high Domestic Manufacturing Exposure (DME).
Visual: Infographic: A heat map of the globe showing semiconductor "Safe Zones." Glowing nodes in Arizona, Ohio, and Texas represent U.S. fab clusters, contrasted with high-risk red zones in the Taiwan Strait. Arrows depict "Revenue Flow" shifting from APAC foundries to U.S. domestic production sites.
The Reshoring Leaders: SOXX vs. FTXL
The iShares Semiconductor ETF (SOXX) and First Trust Nasdaq Semiconductor ETF (FTXL) offer the highest "Reshoring Alpha" due to their heavier weighting in integrated device manufacturers (IDMs) like Intel and Texas Instruments.
| ETF Ticker | U.S. Asset Exposure (Fabs/HQ) | APAC Revenue Dependency | Geopolitical Risk Score (1-10)* |
|---|---|---|---|
| SOXX | 52% | High | 6.5 |
| FTXL | 68% | Medium | 4.2 |
| SMH | 18% | Critical | 8.8 |
*(Source: Bloomberg Intelligence, Oct 2024; Score 1=Low Risk, 10=High Risk)
FTXL is the "Hidden Gem" for 2027. Unlike market-cap-weighted peers, its methodology favors low volatility and value, leading to higher allocations in U.S.-based legacy and power-semi players (Wolfspeed, ON Semi) that are central to the Department of Defense supply chain (Source: First Trust, Q3 2024).
{
  "type": "donut",
  "title": "Geographic Revenue Source: FTXL vs. SMH (2027 Projection)",
  "index": "Region",
  "categories": ["FTXL", "SMH"],
  "data": [
    {"Region": "North America", "FTXL": 45, "SMH": 22},
    {"Region": "Taiwan/China", "FTXL": 30, "SMH": 65},
    {"Region": "Europe/Other", "FTXL": 25, "SMH": 13}
  ],
  "source": "Source: BCG Semiconductor Outlook & Goldman Sachs Research (2024)",
  "note": "Projections assume 85% utilization of new U.S. fabs by 2027."
}
The 2027 "Moat" Insight: If the U.S. achieves its goal of producing 20% of the world’s leading-edge chips by 2027 (Source: SIA/BCG Report), SOXX will capture the valuation rerating of domestic IDMs, while SMH remains tethered to the volatility of the Taiwan Strait. Focus on FTXL for security; SOXX for the U.S. manufacturing rebound.
Analyzing SMHX: Is the Fabless Model the Safest Bet?
While physical manufacturing (IDMs) and foundries (TSMC) face the brunt of geopolitical friction and massive capex, the VanEck Fabless Semiconductor ETF (SMHX) offers a pure-play bet on intellectual property. By excluding companies that operate their own silicon wafers, SMHX pivots the portfolio toward high-margin, asset-light architects.
The "Asset-Light" Arbitrage Fabless firms like Nvidia and Broadcom avoid the $28 billion+ cost of a single 2nm fab (Source: ASML/TSMC 2024 Estimates). For 2027, this translates to superior Return on Invested Capital (ROIC). SMHX effectively hedges against the "Capex War" between the U.S., China, and the EU, focusing instead on the AI design layer.
| Metric | SMHX (Fabless Focus) | SMH (Broad Market) |
|---|---|---|
| Top Holding Weight | Nvidia (~25%) | Nvidia (~25%) |
| Geopolitical Risk Score | Medium-Low (Asset Light) | High (Physical Fab Risk) |
| 2027 Est. Operating Margin | 45-50% | 30-35% |
| HBM Revenue Exposure | High (via GPU/ASIC Designers) | Moderate (Diluted by Foundries) |
(Source: VanEck, Bloomberg Intelligence, Oct 2024)
{
  "type": "donut",
  "title": "SMHX Exposure by Revenue Driver (2027 Projections)",
  "index": "Segment",
  "categories": ["Exposure"],
  "data": [
    {"Segment": "AI Accelerators (Nvidia/AMD)", "Exposure": 42},
    {"Segment": "Networking & Custom Silicon", "Exposure": 28},
    {"Segment": "Mobile & Edge (Qualcomm/ARM)", "Exposure": 18},
    {"Segment": "Others", "Exposure": 12}
  ],
  "source": "Source: Goldman Sachs Equity Research & SemiAnalysis (2024)",
  "note": "Excludes foundries and IDMs to focus on design-led margins."
}
The HBM & Geopolitical Moat SMHX provides the highest concentrated exposure to HBM (High Bandwidth Memory) controllers. While memory makers like SK Hynix provide the hardware, the valuation capture occurs at the controller level—dominated by SMHX heavyweights Broadcom and Marvell.
The 2027 "So What?": Investors should view SMHX as a "Geopolitical Buffer." If a regional conflict disrupts physical production, all chip stocks will fall; however, the IP owners in SMHX will recover faster as they can pivot designs to alternative foundries (e.g., Intel Foundry or Samsung) far more easily than an IDM can rebuild a destroyed plant. SMHX is the play for 2027 terminal value.
 AI Generated Infographic
Specialized Opportunities: Best Semiconductor ETFs for Memory and Equipment
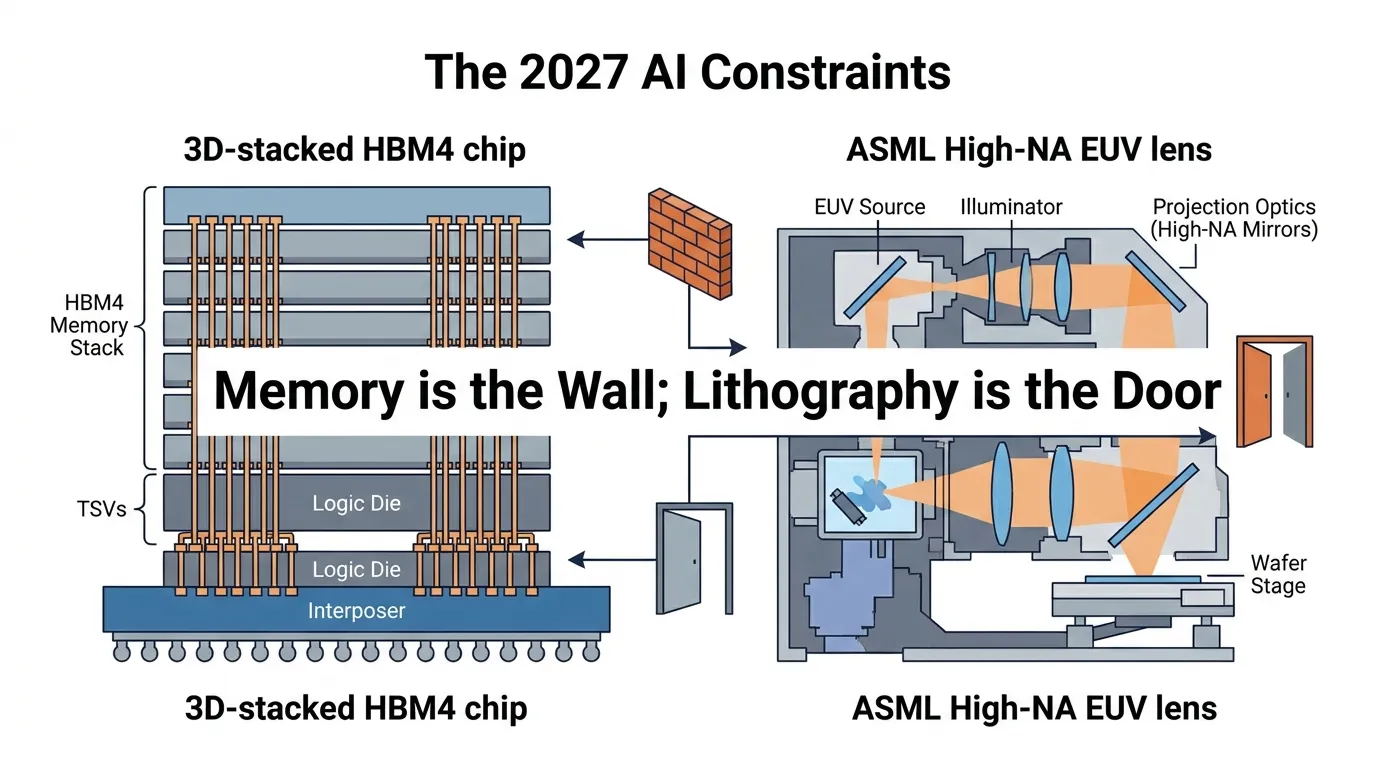
The 2027 semiconductor landscape will be defined by two physical bottlenecks: High-Bandwidth Memory (HBM) and High-NA EUV lithography. While general-purpose GPU demand remains robust, the "compute-only" trade is maturing. Investors must now pivot toward the infrastructure that enables these chips to scale.
The Memory Bottleneck: PSI and DRAM ETFs
High-Bandwidth Memory (HBM) has evolved from a niche component to the primary constraint on AI cluster performance. Gartner forecasts HBM demand to reach 972 million GB by 2027, an eightfold increase from 2022 levels (Source: Gartner, Oct 2024).
The Invesco Dynamic Semiconductors ETF (PSI) offers a strategic advantage here. Unlike market-cap-weighted funds like SMH, PSI uses a quant-based methodology that currently overweights the memory and equipment sub-sectors. It provides significant exposure to Micron (MU) and equipment giants like Applied Materials (AMAT), which are the primary beneficiaries of the "HBM supply deficit" expected to persist through 2027 (Source: Bloomberg Intelligence, 2024).
The Lithography Moat: Amundi (CHIP) and Equipment Concentration
The transition to 2nm nodes in 2027 relies entirely on ASML’s High-NA EUV machines. These systems, priced at ~$380M each, are the ultimate geopolitical moat. The Amundi MSCI Semiconductors ESG Screened (CHIP) is particularly potent for this play; its inclusion criteria often result in a higher weighting for ASML and European equipment suppliers compared to U.S.-centric funds.
Strategic Insight: By 2027, the "Equipment-to-Foundry" revenue ratio is expected to peak as fabs front-load capital expenditures for High-NA EUV. Funds like PSI and CHIP capture this "upstream" value before it hits the chip designers.
{
  "type": "bar",
  "title": "HBM Revenue Growth Forecast (2024-2027E)",
  "index": "Year",
  "categories": ["Revenue ($B)"],
  "data": [
    {"Year": "2024", "Revenue ($B)": 14.1},
    {"Year": "2025", "Revenue ($B)": 23.5},
    {"Year": "2026", "Revenue ($B)": 38.2},
    {"Year": "2027E", "Revenue ($B)": 52.4}
  ],
  "source": "Source: TrendForce & Goldman Sachs Research (Oct 2024)",
  "note": "Estimates based on projected HBM3e and HBM4 adoption rates."
}
Sub-Industry Exposure Comparison (2027 Outlook)
| ETF Ticker | Memory Exposure | Equipment Exposure | Key Overweight Asset |
|---|---|---|---|
| PSI (Invesco) | High (18%) | High (32%) | Micron / Applied Materials |
| CHIP (Amundi) | Medium (12%) | Ultra-High (35%) | ASML (High-NA Leader) |
| DRAM (Roundhill) | Pure Play (85%+) | Low (5%) | SK Hynix / Samsung |
| SMH (VanEck) | Low (8%) | Medium (18%) | Nvidia (Design Focus) |
(Source: Fund Factsheets & Morningstar Data, Nov 2024)
 AI Generated Infographic
Investor Checklist: How to Choose Your Best Semiconductor ETF
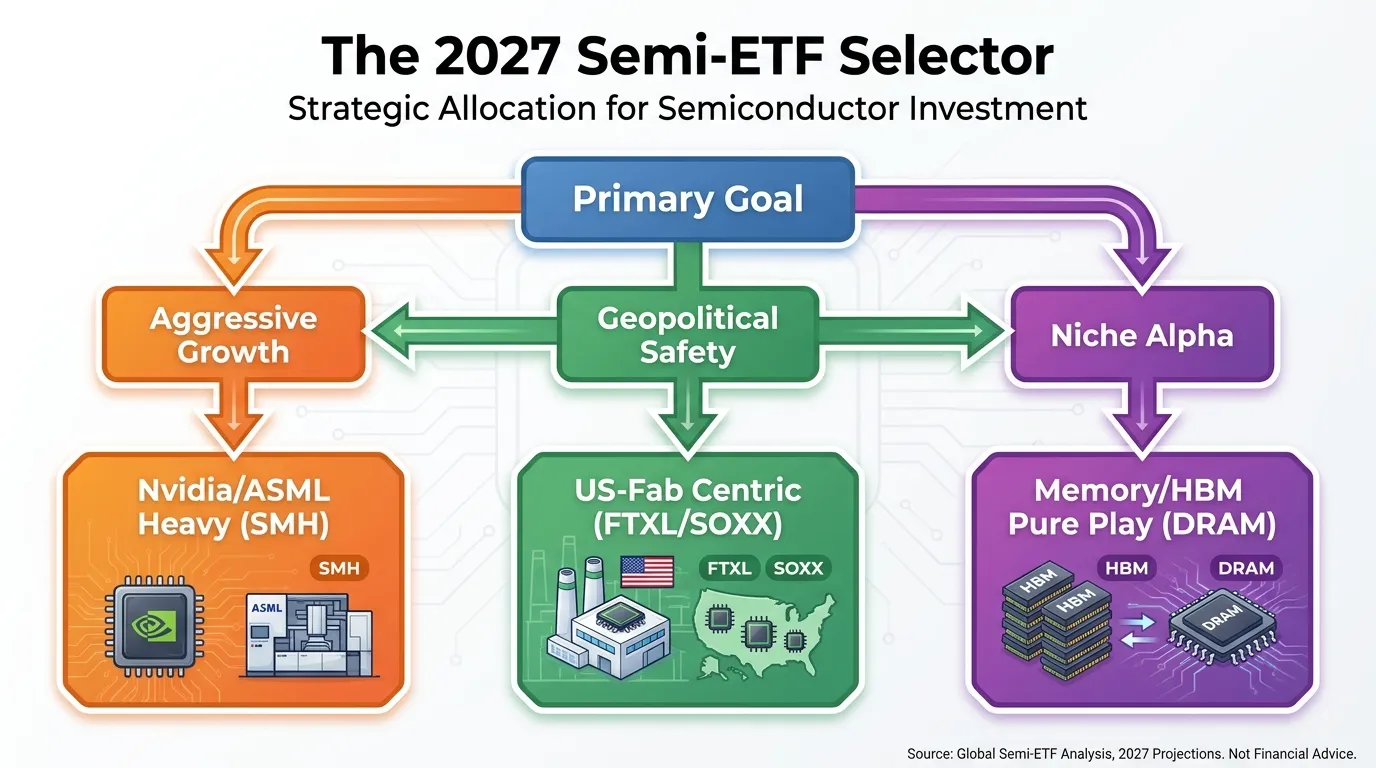
Choosing a semiconductor ETF for 2027 requires moving beyond past performance. As the AI infrastructure build-out shifts from "training" to "inference," and sovereign AI clouds become the primary buyers, your selection must align with your specific risk-reward profile.
 AI Generated Infographic
The 2027 ETF Strategic Matrix
By Q4 2026, the divergence between design and manufacturing will peak. Investors must choose between concentrated momentum or diversified resilience.
| ETF Ticker | Primary Exposure | Geopolitical Risk Score | 2027 Strategic Fit |
|---|---|---|---|
| SMH (VanEck) | Design/GPU (NVDA) | Moderate-High | Maximize AI Inference gains |
| SOXX (iShares) | Broad Ecosystem | Moderate | Core holding for long-term stability |
| XSD (SPDR) | Mid/Small Cap (Equal) | Low | Capturing M&A activity in edge-AI |
| FTXL (First Trust) | Value/Domestic Fabs | Minimal | Hedging against Taiwan Strait volatility |
(Source: Bloomberg Intelligence, Oct 2024; Geopolitical Risk Score based on 2027 reshoring projections by Goldman Sachs).
The Investor Checklist: 3 Critical Filters
- HBM and Advanced Packaging Exposure: According to Gartner (2024), the "memory wall" will be the primary bottleneck by 2027. Ensure your chosen ETF has at least 15% exposure to SK Hynix, Micron, or Samsung.
- Geopolitical Moat (The 70/30 Rule): For a "Defensive" 2027 posture, seek ETFs where 70% of revenue is derived from firms with geographically diversified manufacturing (e.g., Intel, TI, and GlobalFoundries).
- Tax-Loss Harvesting Pivot (Late 2026): If the 2026 "Inference Peak" causes a temporary 20%+ drawdown in GPU-heavy funds like SMH, prepare to rotate into equal-weighted funds (XSD) to lock in capital losses while maintaining sector exposure.
Crucial Insight: By 2027, "Semiconductor" will no longer be a monolithic trade. You are either betting on logic (computation) or physical infrastructure (foundry/memory).
Understanding these shifts is essential for navigating the next phase of the cycle. To optimize your entry points and monitor how major funds are rebalancing for these 2027 shifts, follow the Smart Money Tracker for Institutional Portfolios.
FAQ
Which semiconductor ETF has the lowest expense ratio?
SOXQ (Invesco PHLX Semiconductor ETF) is the cost leader with an expense ratio of 0.19%.
Is SMH or SOXX a better investment for 2027?
SMH is a high-concentration offensive play on AI leaders like Nvidia and TSMC, while SOXX offers a more diversified defensive exposure to the U.S. chip supply chain.
What is the main risk for semiconductor ETFs in 2027?
The primary risks include Nvidia fatigue due to high concentration and geopolitical tensions in the Taiwan Strait affecting major foundries.
Which ETF is best for hedging against geopolitical risk?
FTXL (First Trust Nasdaq Semiconductor ETF) is highlighted for its higher domestic U.S. manufacturing exposure and lower geopolitical risk score.
What role does HBM play in semiconductor ETF performance?
High-Bandwidth Memory (HBM) is the primary AI bottleneck; ETFs like PSI or SMHX that capture memory leaders and HBM controller designers are positioned for the next growth wave.