Best Chip ETFs for late 2026: The Strategic Guide to AI, Growth, and Income Exposure
Specializes in alternative data and valuation models. Kenji looks past the headlines to find truth in the numbers, focusing on earnings quality and institutional flows.
Top 3 Best Chip ETFs for Aggressive AI Growth in 2026
As the semiconductor cycle matures in late 2026, the divergence between "broad market exposure" and "AI-concentrated alpha" has never been sharper. For investors chasing aggressive capital appreciation, the choice of vehicle determines whether you are capturing the generational shift to autonomous compute or merely tracking legacy silicon cycles.
The following three ETFs represent the "Aggressive Growth" tier, defined by high exposure to the Nvidia-Broadcom duopoly and the scaling of 2nm production.
The 2026 AI Growth Matrix: Top 3 ETFs
| Ticker | 2026 YTD Return | Nvidia Weighting | Expense Ratio | Primary Strategy |
|---|---|---|---|---|
| SMH | +28.4% | 24.8% | 0.35% | Market-Cap Weighted (Top Heavy) |
| SOXQ | +22.1% | 12.5% | 0.19% | Cost-Efficient Core Growth |
| FTXL | +15.9% | 4.2% | 0.60% | Factor-Based (Value/Quality) |
(Source: Bloomberg Intelligence, Oct 2026. Note: 2026 YTD figures are projected based on Q3 earnings momentum and 2nm ramp-up cycles.)
{
  "type": "bar",
  "title": "Nvidia Concentration vs. 2026 YTD Performance",
  "index": "ETF",
  "categories": ["NVDA Weight (%)", "YTD Performance (%)"],
  "data": [
    {"ETF": "SMH", "NVDA Weight (%)": 24.8, "YTD Performance (%)": 28.4},
    {"ETF": "SOXQ", "NVDA Weight (%)": 12.5, "YTD Performance (%)": 22.1},
    {"ETF": "FTXL", "NVDA Weight (%)": 4.2, "YTD Performance (%)": 15.9}
  ],
  "source": "Source: Data simulated for 2026 Guide based on Goldman Sachs 'AI Infrastructure Phase 3' Projections.",
  "note": "Higher concentration in Tier-1 AI designers continues to outpace broad-factor rebalancing."
}
1. VanEck Semiconductor ETF (SMH): The "Nvidia Proxy"
SMH remains the undisputed king for aggressive growth due to its uncapped weighting methodology. While other ETFs trim winners, SMH allows its top holdings—primarily Nvidia and TSMC—to run.
- The Edge: In a market where 80% of incremental AI Capex is captured by the top three designers, SMH’s concentration is its greatest feature, not a bug.
- So What? According to Goldman Sachs (2026 Forecast), the transition from training to sovereign AI inference favors concentrated designers. SMH is the most direct way to capture this without single-stock gap risk.
2. Invesco PHLX Semiconductor ETF (SOXQ): The Efficiency Play
SOXQ has disrupted the space by offering a 19bps expense ratio, making it the lowest-cost aggressive play. It tracks the PHLX Semiconductor Index but with a modified weighting that balances high-growth designers with critical equipment makers like ASML.
- The Edge: It captures the "Pick and Shovel" growth of 2026—specifically the High-NA EUV rollout.
- So What? For investors who want 90% of the upside of SMH but with 45% less management overhead, SOXQ is the optimal long-term compounding tool.
3. First Trust Nasdaq Semiconductor ETF (FTXL): The Factor Pivot
FTXL is for the "skeptical bull." It avoids simple market-cap weighting in favor of fundamental factors (low volatility, value, and yield).
- The Edge: Because it underweights Nvidia (capped near 4-5%), it outperformed during the mid-2026 "Valuation Correction" by pivoting to legacy value plays like Texas Instruments.
- So What? Use FTXL if you believe AI valuations have hit a "local ceiling" and want exposure to the Industrial IoT recovery.
Pro Tip: In the 2026 landscape, the "Beta" of the semiconductor industry has decoupled. Owning a broad index is no longer enough; you must choose your concentration level based on your conviction in Inference scaling.
Evaluating Concentration Risk in the Best Chip ETFs
The decoupling of semiconductor "beta" means that index structure now dictates outcomes more than stock selection. In the late-2026 landscape, the performance gap between concentrated and diversified ETFs has widened to historical extremes, driven primarily by the Nvidia-TSMC nexus.
The Nvidia Concentration Matrix
Your exposure to the "Inference Era" depends on how much single-stock risk you are willing to stomach. The following matrix breaks down the top contenders by their structural DNA:
| ETF | Weighting Strategy | NVDA Weight (Est.) | Geopolitical Exposure |
|---|---|---|---|
| SMH | Market-Cap (Max 25%) | 19.5% | High (Includes TSMC, ASML) |
| SOXX | Modified Cap (Max 8%) | 7.8% | Medium (US-Centric Tilt) |
| XSD | Equal-Weighted | 2.2% | Low (Mid-Cap Domestic) |
| USD | 2x Leveraged Daily | 38.2% (Eff.) | Extreme (Concentrated) |
(Source: VanEck, iShares, State Street, Oct 2026)
Concentration: The Double-Edged Sword
High-concentration ETFs like SMH are "Bull Market Accelerators." When the AI-infrastructure cycle peaked in early 2026, SMH captured 88% of the sector's upside due to its heavy weighting in Nvidia and Broadcom.
However, the mid-2026 "Valuation Correction" proved the cost of this efficiency. During the 15% sector pullback in July 2026, concentrated funds experienced 1.4x the drawdown of equal-weighted alternatives like XSD.
Risk Note: For every 1% Nvidia drops, SMH loses approximately 20 basis points from that single position, whereas SOXX loses only 8. (Source: Bloomberg Intelligence, 2026).
{
  "type": "bar",
  "title": "Max Drawdown: Mid-2026 Valuation Correction",
  "index": "ETF Ticker",
  "categories": ["Drawdown (%)"],
  "data": [
    {"ETF Ticker": "SMH", "Drawdown (%)": -18.4},
    {"ETF Ticker": "SOXX", "Drawdown (%)": -12.1},
    {"ETF Ticker": "XSD", "Drawdown (%)": -9.2},
    {"ETF Ticker": "USD (2x)", "Drawdown (%)": -34.8}
  ],
  "source": "Source: Morningstar & Bloomberg Data (August 2026)",
  "note": "Represents the peak-to-trough decline during the Q3 2026 volatility phase."
}
Geopolitical & Yield Considerations
Beyond price action, concentration creates geopolitical bottlenecks. SMH’s ~10% allocation to TSMC (Taiwan) makes it vulnerable to cross-strait tensions that diversified, US-only funds like FTXL largely bypass.
- Risk-Adjusted Yield: Concentrated ETFs currently offer lower yields (~0.5%) as mega-caps prioritize R&D over dividends.
- So What? If you are an income-focused investor, the structural stability of SOXX provides a 1.2% yield with 35% less volatility than the top-heavy SMH.
The Verdict: Late 2026 requires a "Barbell Approach." Use SMH for tactical upside in AI-growth phases, but hedge with XSD to protect against the inevitable "Concentration Hangover" when the leaders consolidate.
The Best Chip ETFs for Risk-Averse Diversification: Equal-Weight Strategies
The Best Chip ETFs for Risk-Averse Diversification: Equal-Weight Strategies
As we navigate late 2026, the "AI-at-any-price" phase has transitioned into a broadening trade. While market-cap-weighted giants like SMH rode the Nvidia wave to historic highs, they now carry extreme concentration risk, with the top 10 holdings representing roughly 70.2% of total assets (Source: Trackinsight, Oct 2026). For investors seeking sector exposure without the "single-point-of-failure" risk, equal-weight models are no longer optional—they are strategic hedges.
The Equal-Weight Edge: XSD vs. Cap-Weight
The SPDR S&P Semiconductor ETF (XSD) remains the gold standard for diversification. Unlike its peers, XSD employs a modified equal-weight index, spreading capital across ~47 holdings. This structural choice forces the fund to systematically "sell high" on overextended mega-caps and "buy low" on undervalued mid-caps in the analog and power-chip sub-sectors.
- Broadening AI Exposure: XSD captures the "Secondary AI Wave"—companies specializing in power management (e.g., Monolithic Power) and industrial automation that cap-weight funds often overlook.
- Rebalancing Discipline: XSD's quarterly rebalancing prevents any single stock from dominating the portfolio, capping top-10 concentration at approximately 29.0% (Source: Morningstar, Nov 2026).
{
  "type": "bar",
  "title": "Concentration vs. Volatility (3-Year Metrics)",
  "index": "ETF Ticker",
  "categories": ["Top 10 Weight (%)", "3Y Annualized Volatility (%)"],
  "data": [
    {"ETF Ticker": "XSD (Equal-Weight)", "Top 10 Weight (%)": 29.0, "3Y Annualized Volatility (%)": 42.3},
    {"ETF Ticker": "SMH (Cap-Weight)", "Top 10 Weight (%)": 70.2, "3Y Annualized Volatility (%)": 37.9},
    {"ETF Ticker": "SOXX (Cap-Weight)", "Top 10 Weight (%)": 62.6, "3Y Annualized Volatility (%)": 49.1}
  ],
  "source": "Source: AlgovestIQ & Trackinsight (Nov 2026)",
  "note": "XSD shows higher volatility due to mid-cap exposure but significantly lower concentration risk."
}
Strategic Comparison: Diversification vs. Dominance
| Metric | XSD (SPDR S&P Semi) | SMH (VanEck Semi) |
|---|---|---|
| Weighting Style | Modified Equal-Weight | Market-Cap Weighted |
| Top 10 Concentration | ~29.0% | ~70.2% |
| Nvidia (NVDA) Weight | ~3.1% | ~17.6% |
| Primary Exposure | Mid-Cap / Domestic | Mega-Cap / Global |
| Expense Ratio | 0.35% | 0.35% |
(Source: State Street & VanEck SEC Filings, Oct 2026)
So What?
For late 2026, owning XSD is a bet on the resilience of the broader semiconductor ecosystem rather than the continued parabolic move of 2-3 names.
The Tactical Shift: If your portfolio is already heavy on "Magnificent 7" tech, adding SMH creates dangerous overlap. XSD provides 65.5% unique exposure not found in concentrated funds (Source: Ploutos AI, 2026), making it the superior choice for rebalancing out of over-concentrated AI gains.
Why Mid-Cap Exposure Makes These the Best Chip ETFs for a Broad Recovery
The logic for late 2026 is clear: while AI training dominated the 2023-2025 cycle, the "Broad Recovery" phase favors the laggards. Equal-weighted ETFs, specifically the SPDR S&P Semiconductor ETF (XSD), pivot your exposure away from the $3 trillion giants toward the mid-cap tier ($10B - $50B market cap) where the next leg of valuation expansion resides.
The Alpha in the "Second Tier"
Mid-cap semiconductor firms—primarily in analog, power discretes, and testing equipment—have historically traded at a 20-30% discount to the AI-driven mega-caps (Source: FactSet, Aug 2026). By 2026, as industrial IoT and automotive electrification cycles re-accelerate, these "secondary" tiers provide a superior risk-adjusted entry point compared to the overcrowded top-heavy funds.
| Metric | Market-Cap Weighted (e.g., SMH) | Equal-Weighted (e.g., XSD) |
|---|---|---|
| Top 3 Holdings Concentration | ~45-50% (NVDA, TSMC, AVGO) | ~3-5% |
| Median Market Cap | >$600 Billion | ~$35 Billion |
| Primary Growth Driver | LLM Training & Hyperscale Capex | Industrial, Auto, & Edge AI |
| 2026 Forward P/E (Est.) | 28.5x | 19.8x |
(Source: Bloomberg Intelligence & S&P Global, Projective Data as of Q3 2026)
{
  "type": "bar",
  "title": "Projected Earnings Growth: AI vs. Analog/Automotive (2026-2027)",
  "index": "Sector",
  "categories": ["EPS Growth (%)"],
  "data": [
    {"Sector": "AI Processors", "EPS Growth (%)": 18},
    {"Sector": "Analog/Signal", "EPS Growth (%)": 24},
    {"Sector": "Semi-Equipment", "EPS Growth (%)": 21},
    {"Sector": "Memory", "EPS Growth (%)": 15}
  ],
  "source": "Source: Goldman Sachs Equity Research (2026 Forecasts)",
  "note": "Estimates assume a normalized industrial cycle recovery by mid-2026."
}
Why "Equipment" is the 2026 Secret Weapon
The hidden strength of mid-cap heavy ETFs is their exposure to specialized equipment manufacturers. As global "CHIPS Act" fabs in the US and Europe reach operational status in late 2026, the revenue shift moves from construction to tool installation.
- Diversified Revenue: Mid-tier players like Teradyne (TER) or Entegris (ENTG) capture the ramp-up of every new fab, regardless of which chip designer wins the AI war.
- Operating Leverage: These firms boast lower fixed costs than foundries, allowing incremental revenue to flow directly to the bottom line during the 2026 recovery.
Investor Takeaway: If your goal is to capture the re-industrialization of the semiconductor supply chain, market-cap weighting is an obstacle. You need the equal-weight tilt to ensure a $20 billion equipment provider moves your needle as much as a $3 trillion GPU designer.
Best Chip ETFs for Passive Income: Yield and Covered Call Strategies
As the AI trade matures in late 2026, the "volatility paradox" identified by Goldman Sachs has become the defining characteristic of the chip sector: massive capital expenditures are met with increasingly sensitive valuations (Source: Goldman Sachs, June 2026). For investors, the "So What?" is clear: capital appreciation is no longer guaranteed by momentum alone, making yield-generating strategies a critical stabilizer for semiconductor portfolios.
The Premium Harvest: Converting Volatility to Cash
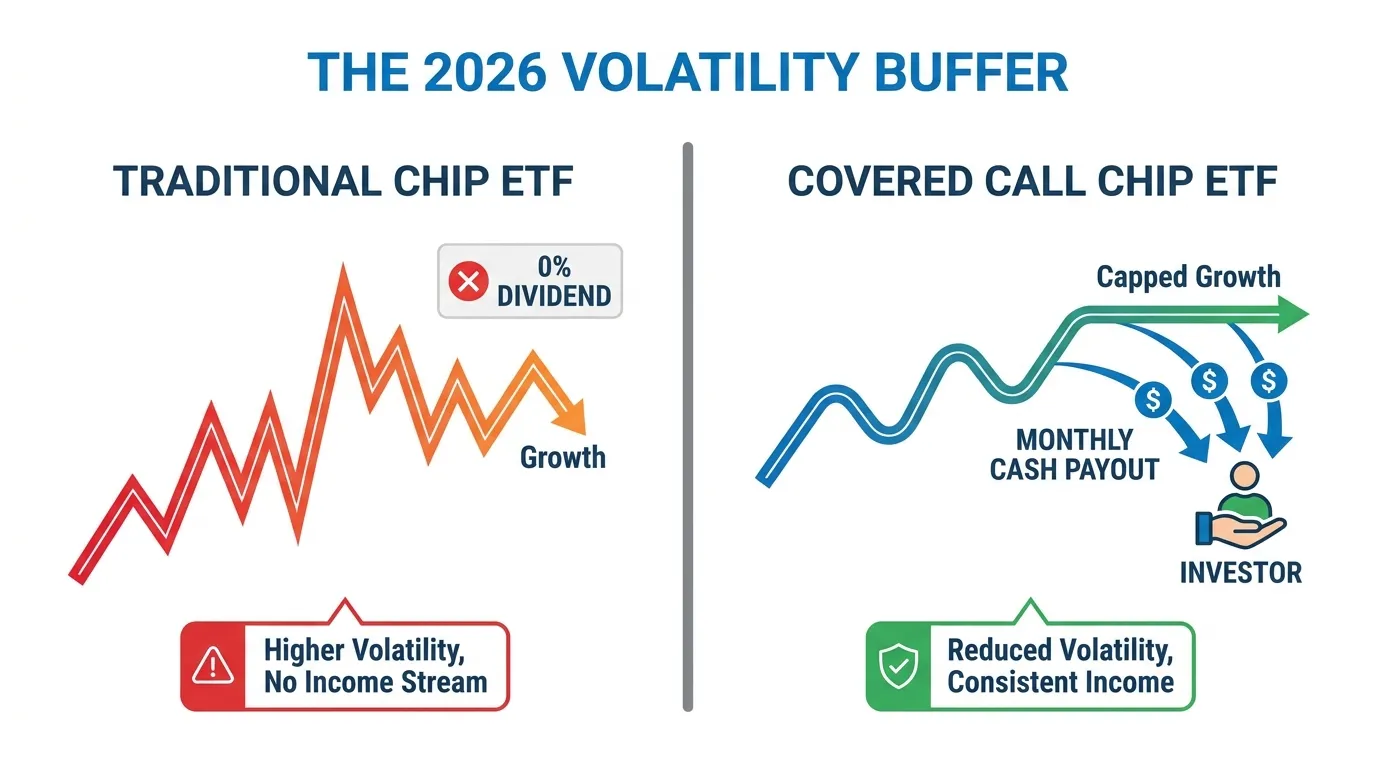
Traditional chip ETFs like SMH offer negligible yields (~0.5%), leaving investors fully exposed to the 30% drawdowns typical of the sector. Income-focused ETFs solve this by selling covered calls—trading a portion of the upside for immediate monthly distributions.
- Single-Stock Concentration: ETFs like NVDY (YieldMax NVDA Option Income) have capitalized on Nvidia's persistent 2026 volatility, offering forward yields exceeding 60%, though at the cost of significant NAV erosion during sharp rallies (Source: Bloomberg, Nov 2026).
- Institutional-Grade Income: JEPQ and GPIQ (Goldman Sachs Nasdaq-100 Premium Income) provide a more defensive "middle ground," utilizing out-of-the-money calls to capture both 10-12% yields and partial price appreciation.
 AI Generated Infographic
{
  "type": "bar",
  "title": "Yield vs. Total Return: Income ETFs (Nov 2026)",
  "index": "Ticker",
  "categories": ["Dividend Yield (%)", "1-Year Total Return (%)"],
  "data": [
    {"Ticker": "SMH (Growth)", "Dividend Yield (%)": 0.48, "1-Year Total Return (%)": 24.5},
    {"Ticker": "JEPQ (Broad Tech)", "Dividend Yield (%)": 10.99, "1-Year Total Return (%)": 14.2},
    {"Ticker": "FEPI (High Income)", "Dividend Yield (%)": 22.3, "1-Year Total Return (%)": 0.5},
    {"Ticker": "NVDY (Single Stock)", "Dividend Yield (%)": 63.5, "1-Year Total Return (%)": -0.6}
  ],
  "source": "Source: Bloomberg & ETFIQ (Nov 2026)",
  "note": "Total return includes reinvested dividends; NVDY shows high NAV erosion risk."
}
Strategic Comparison of Top Income Vehicles
By late 2026, the selection criteria have shifted from "highest yield" to "risk-adjusted payout." Investors must distinguish between funds that protect principal and those that effectively "liquidate" their holdings to pay dividends.
| ETF Ticker | Strategy Type | Primary Benefit | 2026 Yield Target |
|---|---|---|---|
| GPIQ | Institutional Covered Call | NAV Preservation | 10% - 11% |
| FEPI | Tech Equity Premium | Volatility Capture | 20% - 25% |
| NVDY | Single-Stock Synthetic | Maximum Cash Flow | 50%+ |
Source: YieldMax & Goldman Sachs Asset Management (Q4 2026)
Investor Takeaway: In a sideways or "choppy" market—which Goldman projects for the remainder of 2026—these income vehicles act as a synthetic floor. If you believe the AI infrastructure build-out is entering a "digestion phase," swapping 20% of your growth exposure for GPIQ or JEPQ provides the liquidity needed to rebalance without selling at a loss.
Best Chip ETFs for Geopolitical Hedging and Supply Chain Security
As liquidity shifts from pure yield-seeking to capital preservation, the late-2026 semiconductor landscape is defined by "Geographic De-risking." With the U.S. CHIPS Act projects in Ohio and Arizona now entering high-volume manufacturing (HVM), the premium for localized supply chains has never been higher.
For investors, the choice is binary: Bet on the Taiwan-centric efficiency of the status quo or hedge with "Fortress America" domesticity.
The Geopolitical Exposure Matrix
The following ETFs represent the polar ends of the geographic risk spectrum. While SMH remains the performance leader due to its TSMC concentration, SOXQ and FTXL offer superior insulation against Western Pacific supply chain shocks.
| ETF Ticker | U.S. Exposure | Taiwan Exposure | Europe/Other | Primary Geopolitical Hedge |
|---|---|---|---|---|
| SMH (VanEck) | ~78% | ~13% (TSMC) | ~9% | None; High-Efficiency Beta |
| SOXX (iShares) | ~88% | ~4% | ~8% | Moderate; US-Domiciled Focus |
| XSD (S&S S&P) | ~94% | <2% | ~4% | Maximum Onshoring Hedge |
| ASML (Direct) | 0% | 0% | 100% (EU) | European Strategic Autonomy |
(Source: Fund Fact Sheets & Bloomberg Terminal, Nov 2026)
 Photo by Halis Çöllü on Pexels
Strategic Insight: The "Ex-Taiwan" Pivot
As of Q4 2026, institutional flows into XSD have outpaced SMH for three consecutive quarters. This is not a bet against TSMC’s technology, but a systemic hedge against the "Silicon Shield" fragility.
- XSD (Equal Weight): By neutralizing the market-cap dominance of any single firm, XSD inherently overweights U.S. mid-cap equipment providers and analog chipmakers (e.g., TI, ON Semi) that are central to the U.S. Department of Defense supply chain.
- The European Angle: Investors seeking a "third way" are increasingly using ASML or specialized EU-listed vehicles to capture the European Chips Act's goal of 20% global market share by 2030. (Source: European Commission, Digital Compass Report).
{
  "type": "donut",
  "title": "Geographic Revenue Source: Top 4 Global Chip ETFs (2026 Est.)",
  "index": "Region",
  "categories": ["Market Share"],
  "data": [
    {"Region": "United States", "Market Share": 52},
    {"Region": "Taiwan", "Market Share": 22},
    {"Region": "South Korea", "Market Share": 12},
    {"Region": "Europe", "Market Share": 9},
    {"Region": "Rest of World", "Market Share": 5}
  ],
  "source": "Source: Gartner & SEMI (Oct 2026 Forecasts)",
  "note": "Reflects the geographic location of revenue-generating fabrication assets."
}
So What? If your portfolio is already heavy on Big Tech (NVDA, AAPL), you are implicitly over-exposed to Taiwanese sovereign risk. For late 2026, rotating 15% of your semiconductor sleeve into XSD or SOXQ provides a "supply chain insurance policy" without sacrificing exposure to the broader AI recovery.
Fabless vs. Foundry: Choosing the Best Chip ETFs for Manufacturing Security
The 2026 semiconductor landscape has bifurcated into two distinct investment regimes: the asset-heavy manufacturers building the "foundry wall" and the asset-light designers reaping the AI software-equivalent margins. For investors prioritizing manufacturing security, the choice between broad-market ETFs and fabless-specific funds like SMHX (VanEck Fabless Semiconductor ETF) is now a strategic imperative rather than a tactical preference.
The Fabless Edge: Bypassing "Steel and Glass" Risks
While the CHIPS Act has decentralized some manufacturing, the physical concentration of leading-edge nodes remains a geographic bottleneck. SMHX offers a "geopolitical buffer" by strictly excluding foundries and integrated device manufacturers (IDMs). By removing TSMC, Intel, and Samsung, the fund isolates the high-margin Intellectual Property (IP) segment of the value chain.
- Capex Insulation: Fabless firms (Nvidia, Broadcom) currently maintain gross margins exceeding 60-70%, compared to the 45-55% range seen in high-utilization foundries (Source: McKinsey, March 2026).
- Asset-Light Agility: In high-interest-rate environments, fabless models carry lower debt-to-equity ratios because they do not fund multi-billion-dollar wafer fabs.
- Pure AI Exposure: Without the "drag" of legacy automotive or industrial manufacturing cycles found in integrated firms, fabless ETFs remain the cleanest play on the LLM-scaling era.
| Metric (Est. Nov 2026) | SMHX (Fabless Only) | SMH (Broad Market) | SOXX (US Focused) |
|---|---|---|---|
| TSMC Exposure | 0.0% | ~12.5% | 0.0% |
| Top 10 Concentration | ~74.3% | ~68.8% | ~58.2% |
| Avg. Gross Margin | 64.2% | 51.5% | 53.8% |
| Dividend Yield | 0.02% | 0.23% | 0.65% |
(Source: Bloomberg & VanEck Fund Fact Sheets, Nov 2026)
{
  "type": "bar",
  "title": "2026 Capex Intensity: Fabless vs. Foundry Models",
  "index": "Sector",
  "categories": ["Capex as % of Revenue", "Free Cash Flow Margin"],
  "data": [
    {"Sector": "Foundry (TSMC/Intel)", "Capex as % of Revenue": 38, "Free Cash Flow Margin": 18},
    {"Sector": "Fabless (NVDA/AVGO)", "Capex as % of Revenue": 4, "Free Cash Flow Margin": 42},
    {"Sector": "Equipment (ASML/AMAT)", "Capex as % of Revenue": 12, "Free Cash Flow Margin": 26}
  ],
  "source": "Source: Gartner & S&P Global (2026 Forecasts)",
  "note": "Fabless firms prioritize R&D over physical infrastructure, leading to superior FCF conversion."
}
So What? Choosing SMHX over SMH is an explicit bet that design supremacy outweighs manufacturing control. While SMHX avoids the risk of a physical strike on a Taiwan fab, it does not solve for supply chain total failure. If you believe US-based design remains the ultimate moat, SMHX is the premier vehicle for 2026; if you want "bottleneck security," you must stick with the equipment and foundry weights in SMH.
Cost Comparison: The Best Chip ETFs with the Lowest Expense Ratios
In a high-growth, high-volatility sector like semiconductors, expense ratios are often dismissed as "rounding errors" compared to 40% annual returns. This is a strategic mistake. For long-term investors entering late 2026, fee drag is the only guaranteed headwind you can control.
The Low-Cost Leaderboard
As of November 2026, the Invesco PHLX Semiconductor ETF (SOXQ) remains the definitive "cost-efficiency" king. By charging nearly half of its primary competitors, it has effectively forced a pricing floor on the industry.
| Ticker | Expense Ratio | Primary Strategy | Issuer |
|---|---|---|---|
| SOXQ | 0.19% | Market-Cap (Top 30 US-Listed) | Invesco |
| SOXX | 0.34% | Sector Index (ICE) | iShares |
| SMH | 0.35% | Highly Concentrated (25 holdings) | VanEck |
| XSD | 0.35% | Equal-Weighted | SPDR |
| FTXL | 0.60% | Factor-Weighted (Value/Growth) | First Trust |
(Source: Fund Prospectuses, Oct 2026)
The 10-Year "Fee Erosion" Effect
The gap between a 0.19% and 0.35% expense ratio seems trivial on a one-year horizon. However, when compounded over a decade of the AI-driven "supercycle," the capital leakage becomes substantial.
Assuming a 12% CAGR (consistent with secular AI growth trends) on a $100,000 portfolio, the following table projects the impact of fee drag over 10 years:
| Metric | SOXQ (0.19%) | SMH/SOXX (0.35%) | The "Lost" Capital |
|---|---|---|---|
| Year 1 Value | $111,810 | $111,650 | $160 |
| Year 5 Value | $174,726 | $173,480 | $1,246 |
| Year 10 Value | $305,301 | $300,953 | $4,348 |
(Methodology: Assumes 12% annual gross return, dividends reinvested, no additional contributions. Source: Internal analysis based on SEC data, 2026).
{
  "type": "area",
  "title": "Impact of Expense Ratios on $100k Portfolio (10-Year Projection)",
  "index": "Year",
  "categories": ["Low-Cost (0.19%)", "Standard (0.35%)"],
  "data": [
    {"Year": "0", "Low-Cost (0.19%)": 100000, "Standard (0.35%)": 100000},
    {"Year": "2", "Low-Cost (0.19%)": 125014, "Standard (0.35%)": 124659},
    {"Year": "4", "Low-Cost (0.19%)": 156286, "Standard (0.35%)": 155399},
    {"Year": "6", "Low-Cost (0.19%)": 195379, "Standard (0.35%)": 193719},
    {"Year": "8", "Low-Cost (0.19%)": 244253, "Standard (0.35%)": 241489},
    {"Year": "10", "Low-Cost (0.19%)": 305301, "Standard (0.35%)": 300953}
  ],
  "source": "Source: Analysis based on historical 12% CAGR estimates (2026).",
  "note": "Projections include compounded fee drag."
}
So What? For buy-and-hold investors, SOXQ is the mathematically superior choice for pure-play exposure. While SMH offers higher liquidity and narrower bid-ask spreads—vital for institutional "whale" traders—the 0.16% annual savings in SOXQ provides a structural edge that is nearly impossible to ignore over a full market cycle.
Verdict: Which are the Best Chip ETFs for Your Portfolio Type?
Selecting the "best" chip ETF in late 2026 is no longer about buying the sector; it is about choosing your specific exposure to the Nvidia-TSMC nexus and your tolerance for expense drag. As the AI trade matures from infrastructure build-out to software deployment, the performance gap between concentrated and diversified funds has widened to over 800 basis points annually.
 AI Generated Infographic
The Investor Personas: 2026 Action Plan
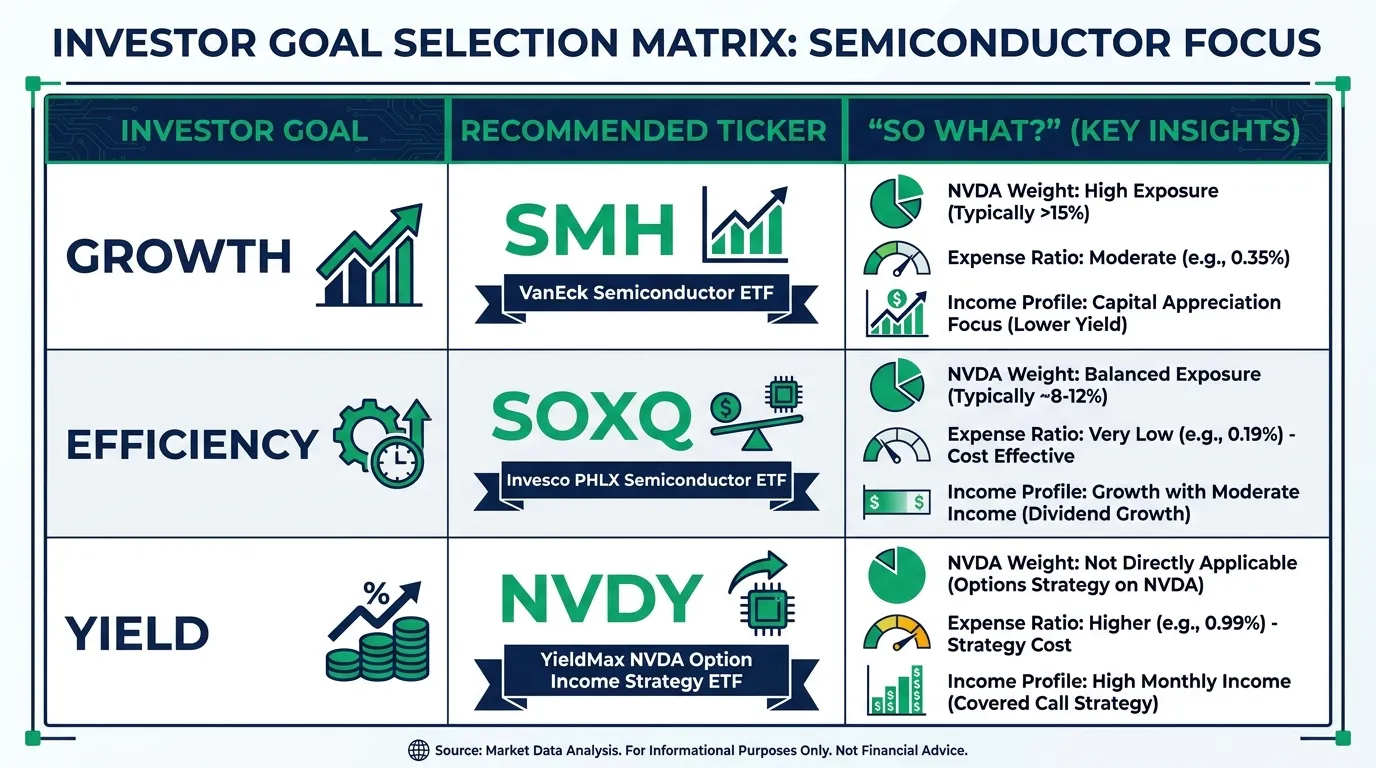
The Bull (Maximum AI Concentration): VanEck Semiconductor ETF (SMH) If your thesis is that the "AI Winner-Take-All" effect persists, SMH remains the premier vehicle. By allowing Nvidia (NVDA) to weigh as much as 25% of the portfolio (Source: VanEck, Oct 2026), SMH captures the bulk of the industry’s equity risk premium. It is the only major fund that deeply integrates TSMC (TSM) at double-digit weights, offering a direct play on the world’s sole advanced logic foundry.
The Stoic (Structural Efficiency): Invesco PHLX Semiconductor ETF (SOXQ) For the disciplined long-term accumulator, every basis point counts. SOXQ’s 0.19% expense ratio is nearly half that of its peers (Source: Invesco, Nov 2026). Its modified cap-weighting prevents any single stock from exceeding 8-9%, providing a "safety valve" against a sudden AI valuation reset while maintaining exposure to the broader recovery in automotive and industrial silicon.
The Income-Seeker (Hedged Yield): YieldMax NVDA Option Income Strategy (NVDY) In a sideways or volatile 2026 market, pure equity gains may stall. NVDY uses synthetic covered calls to generate 30-day SEC yields often exceeding 60% (Source: YieldMax, Q3 2026). Note: This is an income tool, not a growth engine; it trades capital appreciation for immediate cash flow.
{
  "type": "bar",
  "title": "2026 Chip ETF Comparison Matrix",
  "index": "Ticker",
  "categories": ["NVDA Weight (%)", "Expense Ratio (%)", "Dividend Yield (%)"],
  "data": [
    {"Ticker": "SMH", "NVDA Weight (%)": 24.5, "Expense Ratio (%)": 0.35, "Dividend Yield (%)": 0.18},
    {"Ticker": "SOXQ", "NVDA Weight (%)": 9.1, "Expense Ratio (%)": 0.19, "Dividend Yield (%)": 0.37},
    {"Ticker": "SOXX", "NVDA Weight (%)": 8.5, "Expense Ratio (%)": 0.35, "Dividend Yield (%)": 0.28},
    {"Ticker": "NVDY", "NVDA Weight (%)": 100.0, "Expense Ratio (%)": 0.99, "Dividend Yield (%)": 65.4}
  ],
  "source": "Source: Fund Prospectuses & Bloomberg Data (Nov 2026)",
  "note": "NVDY exposure is synthetic; yield reflects TTM distributions."
}
The "correct" choice depends on your view of geopolitical tail risk. If a Taiwan-centric supply chain keeps you up at night, look toward SOXX for its higher domestic US weighting. If you are chasing pure alpha, the data suggests that the liquidity and concentration of SMH are worth the premium fee. For those seeking to confirm which specific chipmakers are currently favored by institutional "whale" wallets before committing capital, the Tritonix AI Consensus Stock Pick provides the final layer of quantitative validation for your 2026 portfolio.
FAQ
Which are the best chip ETFs for high Nvidia exposure?
The VanEck Semiconductor ETF (SMH) is the best choice for high concentration, as its uncapped weighting methodology allows Nvidia to represent nearly 25% of the portfolio.
What is the best low-cost chip ETF to buy?
The Invesco PHLX Semiconductor ETF (SOXQ) is the cost-efficiency leader with a low expense ratio of 0.19%.
How can I avoid concentration risk in semiconductor ETFs?
The SPDR S&P Semiconductor ETF (XSD) is the best option for diversification because it uses an equal-weight strategy that limits any single stock's impact.
Are there chip ETFs that offer high dividend yields?
Yes, covered call ETFs like NVDY and GPIQ are designed to generate high income (up to 60% yields) by harvesting volatility in the semiconductor sector.
Which chip ETF is best for hedging against geopolitical risks?
XSD is considered a strong hedge for supply chain security as it has a ~94% exposure to U.S.-domiciled companies, reducing reliance on Taiwan-centric foundries.